Topic

ITAT Ahmedabad

The ITAT Ahmedabad is a tribunal that hears appeals against income tax orders passed by the Assessing Officer in Gujarat and surrounding regions under the Income-tax Act, 1961.

42 articlesLatest July 2026
Section 263 IT Act | Post-Assessment DVO Report Revealing Understated LTCG Justifies Revision to Protect Revenue : ITAT Ahmedabad
Case Law Analysis
|Income Tax Appellate Tribunal

Section 263 IT Act | Post-Assessment DVO Report Revealing Understated LTCG Justifies Revision to Protect Revenue : ITAT Ahmedabad

The ITAT Ahmedabad affirmed that the Principal Commissioner can invoke revisional powers under Section 263 even after assessment is complete, if a subsequent DVO report proves the original valuation was materially understated, leading to significant revenue loss. This sets a critical precedent for tax authorities to act on credible post-assessment evidence that exposes deliberate or negligent undervaluation of capital assets.

Section 80GGC | Cash-Back Political Donations Are Bogus Entries, Disallowing Deduction: ITAT Ahmedabad
Case Law Analysis
|Income Tax Appellate Tribunal

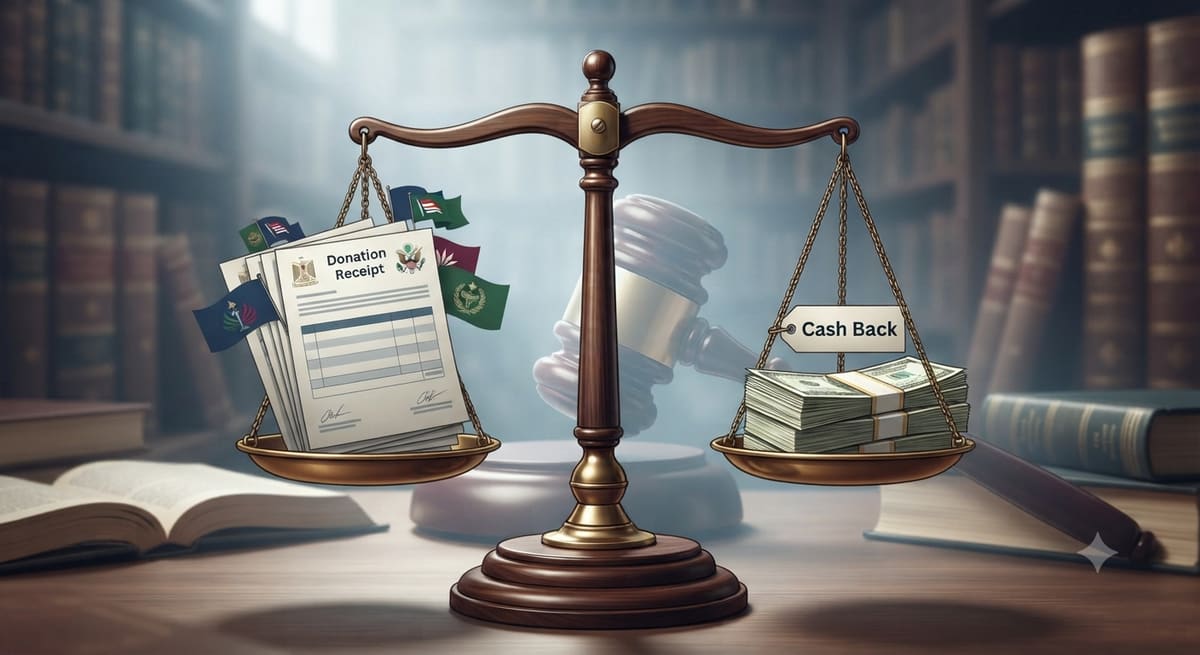
Section 80GGC | Cash-Back Political Donations Are Bogus Entries, Disallowing Deduction: ITAT Ahmedabad

The ITAT Ahmedabad has ruled that donations to political parties accompanied by cash-back arrangements constitute accommodation entries with no genuine economic substance, rendering them ineligible for tax deduction under Section 80GGC. This sets a critical precedent for the Income Tax Department to scrutinize politically linked donations and crack down on shell transactions disguised as electoral funding.

Section 270A IT Act | Penalty for Misreporting Requires Cogent Evidence of False Particulars : ITAT Ahmedabad
Case Law Analysis
|Income Tax Appellate Tribunal

Section 270A IT Act | Penalty for Misreporting Requires Cogent Evidence of False Particulars : ITAT Ahmedabad

ITAT Ahmedabad sets a precedent that penalties under Section 270A for misreporting income cannot be imposed without concrete proof of false particulars or deliberate suppression, even if a deduction is disallowed. This ruling reinforces natural justice principles, protecting taxpayers from arbitrary penalties based solely on disallowed claims.

Section 45 IT Act | Capital Gains Tax Liable Only on Actual Receipt, Not Total Sale Consideration : ITAT Ahmedabad
|Income Tax Appellate Tribunal

Section 45 IT Act | Capital Gains Tax Liable Only on Actual Receipt, Not Total Sale Consideration : ITAT Ahmedabad

ITAT Ahmedabad clarifies that capital gains tax under Section 45 of the Income Tax Act applies only to the amount actually received by a confirming party, not the entire sale consideration. The ruling underscores the need for tax authorities to assess liability based on real receipts, offering relief to taxpayers involved in joint property transactions where proceeds are shared.

Section 12A(1)(ac)(ii) IT Act | Procedural Non-Compliance Cannot Defeat Charitable Trust Registration : ITAT Ahmedabad
Case Law Analysis
|Income Tax Appellate Tribunal

Section 12A(1)(ac)(ii) IT Act | Procedural Non-Compliance Cannot Defeat Charitable Trust Registration : ITAT Ahmedabad

ITAT Ahmedabad overturned the rejection of a charitable trust's registration under Section 12A(1)(ac)(ii), ruling that procedural lapses cannot override substantive compliance with trust objectives. The tribunal emphasized that all mandatory documents were already submitted, reinforcing natural justice over technicalities.

Section 148 IT Act | Notice Beyond Limitation Period Invalid for Reopening Assessment Below ₹50 Lakh : ITAT Ahmedabad
Case Law Analysis
|Income Tax Appellate Tribunal

Section 148 IT Act | Notice Beyond Limitation Period Invalid for Reopening Assessment Below ₹50 Lakh : ITAT Ahmedabad

ITAT Ahmedabad rules that reassessment notices u/s 148 issued beyond the limitation period for escaped income below ₹50 lakh are invalid, setting aside the assessment order and remanding the case for fresh consideration. The tribunal emphasized procedural fairness, requiring the AO to provide recorded reasons and allow the assessee to substantiate capital gains computation.

Section 43 BMA | No Penalty for Foreign Assets Disclosed in Section 153A Return Even If Omitted in Original Return : ITAT Ahmedabad
|Income Tax Appellate Tribunal

Section 43 BMA | No Penalty for Foreign Assets Disclosed in Section 153A Return Even If Omitted in Original Return : ITAT Ahmedabad

ITAT Ahmedabad rules that penalty under Section 43 of the Black Money Act cannot be imposed if foreign assets are disclosed in a return filed under Section 153A, even if omitted in the original return. The decision shields taxpayers from penalties for voluntary disclosures made post-search, reinforcing procedural fairness in foreign asset reporting.

Section 69 Income Tax Act | Unexplained Investment Taxable in Year of Actual Payment, Not Registration Date: ITAT Ahmedabad
Case Law Analysis
|Income Tax Appellate Tribunal

Section 69 Income Tax Act | Unexplained Investment Taxable in Year of Actual Payment, Not Registration Date: ITAT Ahmedabad

The ITAT Ahmedabad has ruled that under Section 69, unexplained investments in immovable property are taxable only in the financial year when the payment is actually made, not when the property is registered. This reinforces that documentary proof of payment timing trumps speculative assumptions by tax authorities, offering clarity to non-residents and cash-based investors facing scrutiny.

Section 154 IT Act | Rectification Cannot Recharacterize Debated Business Income as Unexplained Income Under Section 69A : ITAT Ahmedabad
Case Law Analysis
|Income Tax Appellate Tribunal

Section 154 IT Act | Rectification Cannot Recharacterize Debated Business Income as Unexplained Income Under Section 69A : ITAT Ahmedabad

ITAT Ahmedabad has ruled that an assessing officer cannot use rectification under Section 154 to convert income previously accepted as business income into unexplained income under Section 69A when the classification is genuinely debatable. This protects taxpayers from retrospective reclassification via procedural shortcuts, reinforcing that rectification is for clerical errors only - not for revisiting contested tax positions.

Section 68 IT Act | Repayment via RTGS with Verified Lender Creditworthiness Negates Unexplained Cash Credit Allegation : ITAT Ahmedabad
Case Law Analysis
|Income Tax Appellate Tribunal

Section 68 IT Act | Repayment via RTGS with Verified Lender Creditworthiness Negates Unexplained Cash Credit Allegation : ITAT Ahmedabad

ITAT Ahmedabad has ruled that when a company repays loans through traceable banking channels like RTGS, with documented lender financial capacity and TDS compliance, such transactions cannot be treated as unexplained cash credits under Section 68. This sets a critical precedent for businesses relying on legitimate borrowings, shifting the burden away from mere source-of-funds speculation to verified transactional evidence.

Section 35(2AB) | Weighted Deduction Applies to Gross R&D Expenditure, Not Net After Contract Income Deduction : ITAT Ahmedabad
Case Law Analysis
|Income Tax Appellate Tribunal

Section 35(2AB) | Weighted Deduction Applies to Gross R&D Expenditure, Not Net After Contract Income Deduction : ITAT Ahmedabad

The ITAT Ahmedabad has ruled that companies claiming weighted deduction under Section 35(2AB) may compute the deduction on gross scientific research expenditure, without reducing it by income earned from contract research. This clarifies a long-standing ambiguity and benefits pharmaceutical and tech firms that outsource R&D, ensuring they receive full incentive for domestic innovation spending.

Section 148A IT Act | Reassessment Invalid Without Independent Application of Mind & Proper Notice: ITAT Ahmedabad
Case Law Analysis
|Income Tax Appellate Tribunal

Section 148A IT Act | Reassessment Invalid Without Independent Application of Mind & Proper Notice: ITAT Ahmedabad

ITAT Ahmedabad has ruled that reassessment proceedings under Section 148A are void if the Assessing Officer relies on borrowed satisfaction rather than forming an independent opinion after issuing mandatory notice. This sets a vital precedent for taxpayers: procedural compliance is non-negotiable, and mechanical reopening without reasoned application of mind violates natural justice and renders assessments legally unsustainable.

Section 68 IT Act | Only Profit Element, Not Gross Turnover, Taxable as Unexplained Credit for Land Transactions : ITAT Ahmedabad
Case Law Analysis
|Income Tax Appellate Tribunal

Section 68 IT Act | Only Profit Element, Not Gross Turnover, Taxable as Unexplained Credit for Land Transactions : ITAT Ahmedabad

ITAT Ahmedabad rules that under Section 68 of the Income Tax Act, only the profit component (15% margin) of business receipts from land transactions can be taxed as unexplained credit, not the entire turnover. This sets a precedent for profit estimation in similar cases, shifting the burden of proof toward the revenue after the assessee establishes genuineness of transactions.