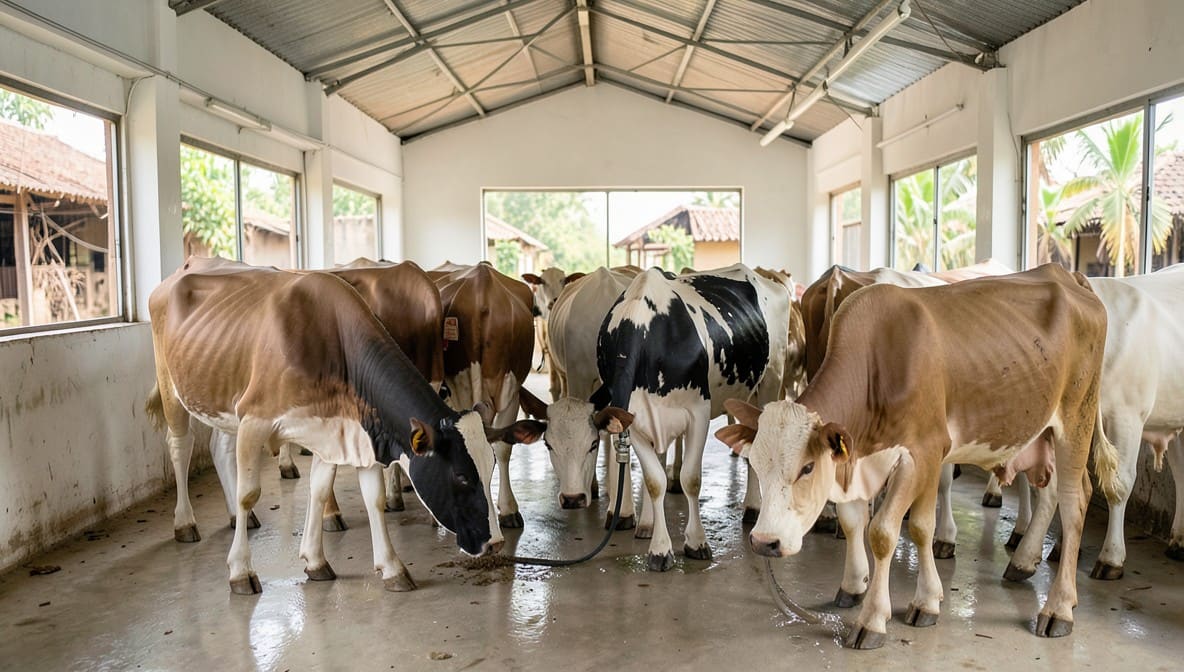
The Income Tax Appellate Tribunal, Delhi Bench 'E', has held that the sale of milk by a gaushala trust is an inseparable and natural consequence of maintaining cows, and thus cannot be treated as a commercial activity attracting the proviso to Section 2(15) of the Income-tax Act, 1961. The Tribunal set aside the rejection of registration under Section 12A and approval under Section 80G, directing the CIT(E) to grant registration to the assessee trust.
Background & Facts
The Genesis of the Trust
The assessee, Shri Gau Sewa Trust, was constituted in the year 2008 vide a trust deed dated 06 November, 2008. The primary objects of the trust include the promotion of gaushalas, protection and welfare of cows, providing food, shelter and medical aid to cows, research and development in the field of gau seva, and promotion of products such as cow milk, cow urine and cow dung. The trust has been regularly filing its return of income and has continuously been granted registration under Section 12AB and approval under Section 80G in preceding years.
Key Facts
- The trust maintains gaushalas and engages in activities related to the welfare of cows.
- The trust produces milk as a natural consequence of maintaining cows, which is then sold to sustain the trust's operations.
- The trust applied for renewal of registration under Section 12A(1)(ac)(ii) on 30 September, 2025.
- The Learned Commissioner of Income Tax (Exemptions), Delhi, rejected the application for registration under Section 12A and approval under Section 80G vide orders dated 26 May, 2026 and 22 May, 2026, respectively.
- The rejection was primarily on the ground that the trust's receipts from the sale of milk exceeded 20% of its total receipts, and thus its activities were considered commercial in nature, violating the proviso to Section 2(15) of the Act.
Procedural History
- 06 November, 2008: Trust deed executed constituting Shri Gau Sewa Trust.
- 30 September, 2025: Assessee filed application for renewal of registration under Section 12A(1)(ac)(ii).
- 26 May, 2026: CIT(E) rejected the application for registration under Section 12A.
- 22 May, 2026: CIT(E) rejected the application for approval under Section 80G.
- 13 July, 2026: Appeals heard by ITAT Delhi Bench 'E'.
- 13 July, 2026: Orders pronounced by ITAT Delhi Bench 'E'.
Relief Sought
The assessee sought quashing of the orders dated 26 May, 2026 and 22 May, 2026, and a direction to the CIT(E) to grant registration under Section 12A and approval under Section 80G.
The Legal Issue
The central question was whether the sale of milk by a gaushala trust, which is a natural consequence of maintaining cows for charitable purposes, constitutes a commercial activity under the proviso to Section 2(15) of the Income-tax Act, 1961, thereby disqualifying the trust from registration under Section 12A and approval under Section 80G.
Arguments Presented
For the Appellant
The learned Counsel for the assessee relied on the decision of the ITAT, Ahmedabad Bench in Sabarmati Ashram Gaushala Trust v. ADIT(Exemption) - [2013] 25 ITR (Trib) 701 (Ahd.), which held that the sale of milk by a gaushala trust is merely incidental to carrying out the charitable objects and does not involve any element of profit motive. The Counsel also relied on the affirmation of this decision by the Hon'ble Gujarat High Court in Director of Income-tax (Exemption) v. Sabarmati Ashram Gaushala Trust - [2014] 362 ITR 539 (Guj.). The Counsel argued that the production of milk is an inseparable and natural consequence of maintaining cows, and its sale is for the purpose of sustaining the trust's charitable activities.
For the Respondent
The Learned CIT-DR argued that the assessee's receipts from the sale of milk exceeded 20% of its total receipts, and thus the trust's activities were commercial in nature, attracting the proviso to Section 2(15) of the Act. The Respondent relied on the judgment of the Hon'ble Supreme Court in ACIT(Exemptions) v. Ahmedabad Urban Development Authority in Civil Appeal No.21762 of 2017, though the Counsel did not elaborate on its application to the facts of the case.
The Court's Analysis
The ITAT Delhi Bench 'E' examined the nature of the assessee's activities and the objects of the trust. The Tribunal noted that the trust's primary object is the protection and welfare of cows, and the sale of milk is an inseparable and natural consequence of maintaining cows. The Tribunal observed that milk cannot be allowed to go waste and must be disposed of, and the sale proceeds are utilized for maintaining the gaushala and carrying out the charitable objects of the trust.
The Tribunal distinguished the judgment in ACIT(Exemptions) v. Ahmedabad Urban Development Authority (supra), noting that the Hon'ble Supreme Court did not hold that registration of such an institution is liable to be cancelled or refused merely because certain receipts are alleged to be commercial in nature. The Tribunal relied on the decision in Sabarmati Ashram Gaushala Trust (supra), which held that the sale of milk was merely incidental to carrying out the charitable objects and there was no element of profit motive.
The Tribunal concluded that the sale of milk cannot be considered as commercial in nature, as it is incidental to the trust's charitable activities. The Tribunal held that the learned CIT(E) erred in rejecting the assessee's application for registration under Section 12A and approval under Section 80G.
"Merely because the milk so obtained is sold and the sale proceeds are utilized for maintaining the gaushala and carrying out the charitable objects of the trust, it cannot be said to be carrying out the commercial diary or carrying on the business in milk."
The Verdict
The ITAT Delhi Bench 'E' allowed both appeals filed by the assessee. The Tribunal set aside the orders dated 26 May, 2026 and 22 May, 2026, and directed the Learned Commissioner of Income Tax (Exemptions), Delhi, to grant registration to the assessee trust under Section 12A and approval under Section 80G within 8 weeks from the date of the order.
What This Means For Similar Cases
Sale of By-Products Is Incidental to Charitable Activities
Practitioners must argue that the sale of by-products, such as milk, cow urine, or cow dung, by a trust engaged in charitable activities like gau seva, is incidental to the trust's primary objects. The incidental nature of such sales does not convert the trust's activities into commercial activities under the proviso to Section 2(15).
- The trust's primary object must be charitable in nature.
- The sale of by-products must be a natural consequence of the charitable activities.
- The proceeds from such sales must be utilized for the trust's charitable purposes.
Registration Cannot Be Denied Solely on Receipts from Incidental Activities
The decision clarifies that registration under Section 12A and approval under Section 80G cannot be denied solely on the ground that the trust earns receipts from activities that are incidental to its charitable objects. The focus must remain on the primary objects of the trust and the nature of its activities.
- The trust's activities must primarily be charitable.
- Receipts from incidental activities do not automatically disqualify the trust from registration.
- The trust must demonstrate that its primary objects are charitable and that any commercial receipts are incidental and utilized for charitable purposes.