Tribunals and Commissions judgments

1770 Tribunals and Commissions judgments explained in plain English: what was decided, the law applied and why it matters. Page 51 of 74.

Technical Resignation Does Not Invalidate Cleared Departmental Exam | Estoppel & Legitimate Expectation Bar Re-Examination Demand : CAT Allahabad
Case Law Analysis
|Central Administrative Tribunal

Technical Resignation Does Not Invalidate Cleared Departmental Exam | Estoppel & Legitimate Expectation Bar Re-Examination Demand : CAT Allahabad

CAT Allahabad rules that an officer who cleared a departmental exam in a prior posting retains that qualification after a technical resignation, and denying promotion on grounds of re-examination violates principles of estoppel and legitimate expectation. The ruling protects government employees from arbitrary re-testing demands post-resignation.
Section 30(2) IBC | Promoter's Restructuring Plan Invalid Without CIRP Compliance : NCLAT
Case Law Analysis
|National Company Law Appellate Tribunal

Section 30(2) IBC | Promoter's Restructuring Plan Invalid Without CIRP Compliance : NCLAT

NCLAT rules that a promoter's restructuring proposal cannot be treated as a valid Resolution Plan under the Insolvency and Bankruptcy Code unless it complies with Section 30(2) and the formal Corporate Insolvency Resolution Process. The ruling reinforces that informal settlements bypassing statutory safeguards are inadmissible, impacting creditors' rights and insolvency proceedings.

Voluntary Service Tax Payment Before SCN Bars Penalties Under Sections 78 & 77 | CESTAT Hyderabad Upholds Penalty Waiver for Bonafide Disclosure
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Voluntary Service Tax Payment Before SCN Bars Penalties Under Sections 78 & 77 | CESTAT Hyderabad Upholds Penalty Waiver for Bonafide Disclosure

CESTAT Hyderabad ruled that voluntary payment of service tax and interest before issuance of a Show Cause Notice (SCN), coupled with a bonafide belief and no suppression of facts, invalidates penalties under Sections 78 and 77 of the Finance Act. The decision reinforces the principle that proactive compliance can shield taxpayers from punitive measures, offering relief to businesses under the Reverse Charge Mechanism.

Section 73(1) Finance Act 1994 | Extended Limitation Period for Service Tax Demands Requires Proof of Wilful Suppression with Intent to Evade : CESTAT Chennai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Section 73(1) Finance Act 1994 | Extended Limitation Period for Service Tax Demands Requires Proof of Wilful Suppression with Intent to Evade : CESTAT Chennai

CESTAT Chennai sets aside a service tax demand as time-barred, ruling that the extended limitation period under Section 73(1) of the Finance Act 1994 mandates proof of wilful suppression with intent to evade tax, not mere non-payment or procedural lapses. The decision underscores the high evidentiary threshold for tax authorities to invoke extended limitation periods against assessees.

Section 68 IT Act | Unexplained Cash Credit Cannot Be Imputed to Opening Balances : ITAT Agra Bars Addition for Prior-Year Loans
Case Law Analysis
|Income Tax Appellate Tribunal

Section 68 IT Act | Unexplained Cash Credit Cannot Be Imputed to Opening Balances : ITAT Agra Bars Addition for Prior-Year Loans

ITAT Agra rules that Section 68 of the Income Tax Act cannot apply to loans outstanding as opening balances from prior assessment years. The tribunal deleted a Rs 6.5 lakh addition, setting a key precedent that unexplained cash credit provisions are inapplicable to pre-existing liabilities, offering relief to taxpayers facing similar assessments.

Unregistered Technical Know-How Not an 'Intellectual Property Right Service' Under Service Tax Law : CESTAT Hyderabad
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Unregistered Technical Know-How Not an 'Intellectual Property Right Service' Under Service Tax Law : CESTAT Hyderabad

CESTAT Hyderabad ruled that payments for unregistered technical know-how from foreign entities do not qualify as 'Intellectual Property Right Services' (IPRS) under service tax law, exempting such transactions from tax liability. The tribunal also clarified that Cenvat credit could not be used for reverse charge liability on such services prior to 01.07.2012, impacting businesses relying on foreign technical collaborations.

FR 56(k) | Mere FIR Registration Does Not Constitute 'Pending Judicial Proceedings' to Block Deemed Voluntary Retirement : CAT
Case Law Analysis
|Central Administrative Tribunal

FR 56(k) | Mere FIR Registration Does Not Constitute 'Pending Judicial Proceedings' to Block Deemed Voluntary Retirement : CAT

Central Administrative Tribunal rules that an FIR alone does not qualify as 'pending judicial proceedings' under Fundamental Rule 56(k), allowing deemed voluntary retirement to take effect upon notice expiry. The ruling clarifies procedural safeguards for government employees facing disciplinary action while seeking voluntary retirement.

Section 12AB & 80G(5) IT Act | Prima Facie Genuineness Suffices for Trust Registration : ITAT Nagpur Overturns Rejection Over Missing Beneficiary Lists
Case Law Analysis
|Income Tax Appellate Tribunal

Section 12AB & 80G(5) IT Act | Prima Facie Genuineness Suffices for Trust Registration : ITAT Nagpur Overturns Rejection Over Missing Beneficiary Lists

ITAT Nagpur rules that charitable trusts cannot be denied registration under Sections 12AB and 80G(5) merely for lacking beneficiary lists or incomplete documentation if prima facie evidence of activities exists. The decision reinforces that procedural gaps alone cannot override substantive compliance, impacting trusts seeking tax exemptions.

Natural Justice in Tax Proceedings | CESTAT Quashes Service Tax Demand Beyond Show Cause Notice Scope : Principal Bench
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Natural Justice in Tax Proceedings | CESTAT Quashes Service Tax Demand Beyond Show Cause Notice Scope : Principal Bench

CESTAT rules that a service tax demand cannot be confirmed under a different taxable head than the one proposed in the Show Cause Notice, reinforcing the principles of natural justice. The decision sets a precedent limiting tax authorities' ability to expand demand classifications post-notice, impacting contractors and service providers under the Finance Act, 1994.

Section 145(3) IT Act | Non-Production of Vouchers Justifies Best Judgment Assessment & Unexplained Cash Addition : ITAT Panaji
Case Law Analysis
|Income Tax Appellate Tribunal

Section 145(3) IT Act | Non-Production of Vouchers Justifies Best Judgment Assessment & Unexplained Cash Addition : ITAT Panaji

ITAT Panaji upholds the rejection of books under Section 145(3) of the Income Tax Act due to non-production of vouchers and audit records, affirming additions for unexplained cash deposits and underreported business profits. The ruling reinforces that failure to substantiate claims with documentary evidence empowers tax authorities to make best judgment assessments, impacting traders and businesses with inadequate record-keeping.

Section 253(3) IT Act | 1-Day Delay in Appeal Condonation Mandatory Where Merits Favor Assessee : ITAT Pune
Case Law Analysis
|Income Tax Appellate Tribunal

Section 253(3) IT Act | 1-Day Delay in Appeal Condonation Mandatory Where Merits Favor Assessee : ITAT Pune

ITAT Pune rules that condonation of a single-day delay in filing an income tax appeal is mandatory if the assessee's case has merit, reinforcing that technicalities cannot override substantial justice. The decision underscores the obligation of appellate authorities to adjudicate appeals on merits rather than dismiss them for minor procedural lapses.

Seniority-Cum-Merit Selection | Notional Promotion Mandatory When Vacancy Unfilled Despite Higher Marks : CAT Allahabad
Case Law Analysis
|Central Administrative Tribunal

Seniority-Cum-Merit Selection | Notional Promotion Mandatory When Vacancy Unfilled Despite Higher Marks : CAT Allahabad

CAT Allahabad rules that denial of promotion despite higher marks and an unfilled vacancy violates principles of equality in employment. The tribunal directs notional promotion with retrospective benefits, setting a precedent for service jurisprudence where administrative discretion cannot override merit-based entitlements.

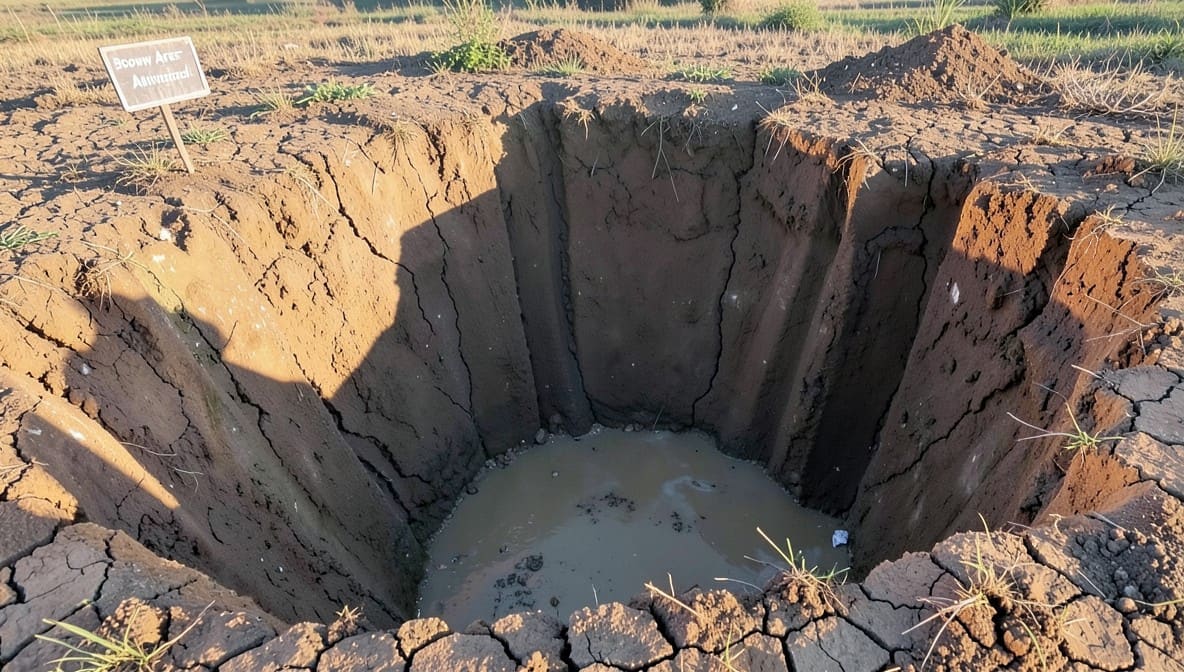
Soil Mining Beyond 2m Depth Illegal Despite EC Exemption for Linear Projects: NGT Upholds Environmental Compensation
Case Law Analysis
|National Green Tribunal

Soil Mining Beyond 2m Depth Illegal Despite EC Exemption for Linear Projects: NGT Upholds Environmental Compensation

NGT confirms that soil mining beyond 2m depth remains illegal even for linear projects exempted from Environmental Clearance (EC). The Tribunal mandates environmental compensation and remediation, setting a precedent for balancing infrastructure development with ecological protection. The ruling impacts project proponents, state authorities, and landowners in linear infrastructure projects.

Section 3(4) Competition Act | CCI Directs DG Probe into VH Group's Exclusive Supply Agreements as Prima Facie Anti-Competitive Vertical Restraints : CCI
Competition Law
|Competition Commission of India

Section 3(4) Competition Act | CCI Directs DG Probe into VH Group's Exclusive Supply Agreements as Prima Facie Anti-Competitive Vertical Restraints : CCI

CCI finds VH Group's exclusive supply agreements for broiler and layer parent stock prima facie violative of Section 3(4) of the Competition Act, 2002, ordering a DG investigation. The ruling signals heightened scrutiny of vertical restraints in poultry breeding, impacting integrated agribusiness players with similar distribution models.

Service Tax Liability | Conversion from Proprietorship to Partnership Requires Fresh Show Cause Notice: CESTAT Quashes ₹69.7 Lakh Demand
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Service Tax Liability | Conversion from Proprietorship to Partnership Requires Fresh Show Cause Notice: CESTAT Quashes ₹69.7 Lakh Demand

CESTAT rules that a partnership firm cannot be held liable for service tax demands arising from its predecessor proprietorship without a fresh show cause notice. The decision underscores the legal distinction between entities, protecting businesses from retrospective tax liabilities post-conversion.

DTAA Royalty Exclusion | Software Licensing Without Copyright Transfer Not Taxable as Royalty or FTS : ITAT Bangalore Affirms Engineering Analysis Precedent
Case Law Analysis
|Income Tax Appellate Tribunal

DTAA Royalty Exclusion | Software Licensing Without Copyright Transfer Not Taxable as Royalty or FTS : ITAT Bangalore Affirms Engineering Analysis Precedent

ITAT Bangalore holds that software licensing fees without transfer of copyright or source code do not constitute 'royalty' or 'fees for technical services' under the Indo-Swiss DTAA, aligning with the Supreme Court's Engineering Analysis ruling. This decision reinforces the distinction between business profits and taxable royalty, impacting multinational software vendors and tax authorities.

Works Contract Service Taxable Only Under Specific Category Post-01.06.2007: CESTAT Hyderabad Bars Vivisection of Composite Contracts
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Works Contract Service Taxable Only Under Specific Category Post-01.06.2007: CESTAT Hyderabad Bars Vivisection of Composite Contracts

CESTAT Hyderabad ruled that composite works contracts cannot be taxed under 'Construction of Complex Service' and barred demands where show cause notices were repeatedly issued, citing the precedent in L&T Ltd. v. CST. The decision reinforces that pre-2007 contracts lacking a specific taxable category cannot be retrospectively taxed, offering relief to developers engaged in integrated township projects.

Section 263 ITA | No Fresh Section 143(2) Notice Required for Revisionary Assessments After PCIT Set-Aside : ITAT Bangalore
Case Law Analysis
|Income Tax Appellate Tribunal

Section 263 ITA | No Fresh Section 143(2) Notice Required for Revisionary Assessments After PCIT Set-Aside : ITAT Bangalore

ITAT Bangalore clarifies that reassessment under Section 263 of the Income Tax Act does not necessitate a fresh notice under Section 143(2), as the proceedings are a continuation of the original assessment. This ruling streamlines procedural compliance for tax authorities and assessees, avoiding redundant notices in set-aside cases.