The Customs, Excise & Service Tax Appellate Tribunal has clarified a critical distinction between private and public roads in the context of service tax exemptions and CENVAT credit eligibility. In a significant ruling, the Tribunal held that even roads constructed within a privately developed industrial park may qualify as public roads if they are accessible to the general public, thereby triggering exemption under Notification No. 25/2012-ST and disqualifying input tax credit claims.
Background & Facts
The Dispute
M/s. Krishna Kunj Pvt. Ltd. developed the Solitaire Industrial Park-II (SIP-II) at Bagru, Jaipur, on land converted from agricultural use under Section 90-A of the Rajasthan Land Revenue Act, 1956, with approval from the Jaipur Development Authority (JDA) dated 08.02.2013. The project included infrastructure development such as landscaping, boundary walls, internal roads, electrical installations, plumbing, sewerage, and construction of water tanks and transformer foundations. These works were executed through contractors under Works Contract Services.
Key Facts
- The appellant constructed internal roads within SIP-II between 2015 and 2017.
- An agreement dated 04.05.2015 was executed with M/s Devi Construction Company for road construction, including paved pathways, kerb stones, and saucer drains.
- The appellant paid service tax under the partial reverse charge mechanism and claimed 60% abatement under Notification No. 30/2012-ST dated 20.06.2012.
- It availed CENVAT credit of Rs. 35,50,371/- on input services used for road construction, treating the roads as private infrastructure.
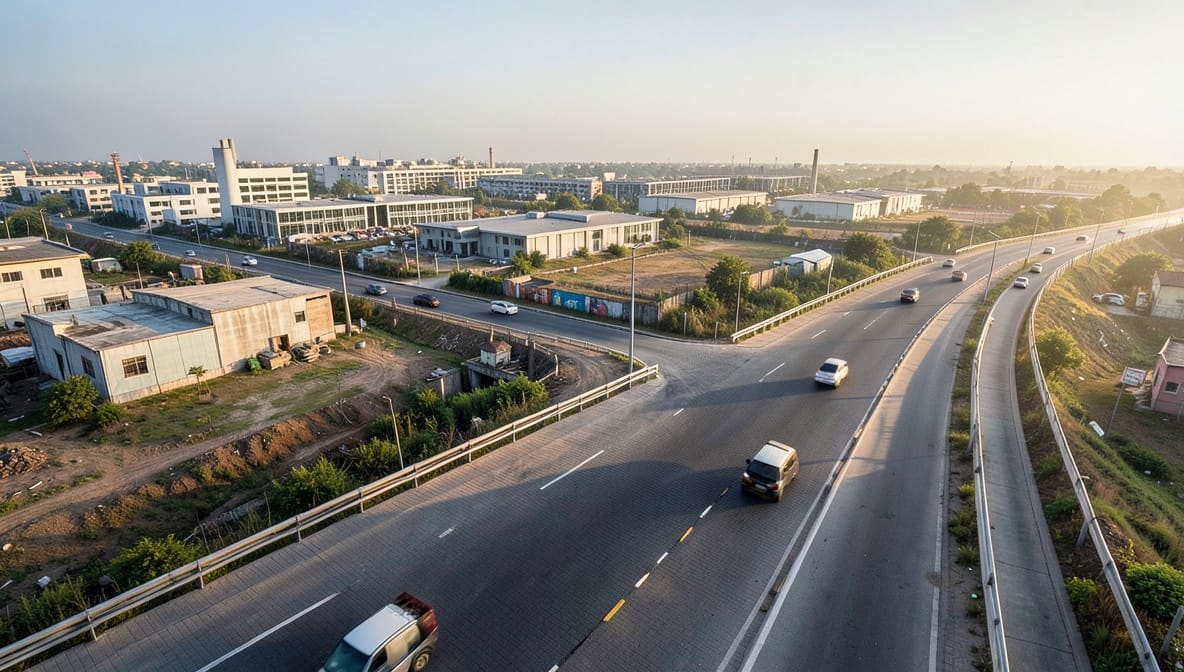
- The Jaipur Master Plan shows that several roads in SIP-II connect to existing public roads, facilitating public access.
- The appellant’s brochure and JDA approvals indicated the park was intended for industrial, residential, EWS/LIG, and commercial use, with roads serving not only park occupants but also the general public.
Procedural History
- 08.11.2019: Show Cause Notice issued under Section 73 of the Finance Act, 1994, alleging wrongful availing of CENVAT credit for the period April 2015 to June 2017.
- 11.03.2021: Order-in-Original confirmed demand of Rs. 35,50,371/- for CENVAT credit reversal, along with interest under Rule 14 of CENVAT Credit Rules, 2004, and penalty under Section 78.
- 30.08.2022: Commissioner (Appeals) upheld the demand, rejecting the appellant’s appeal.
- 09.04.2026: Hearing before the CESTAT Principal Bench, New Delhi.
- 15.05.2026: Final Order pronounced.
Relief Sought
The appellant sought: (1) cancellation of the CENVAT credit demand of Rs. 35,50,371/-; (2) quashing of penalty and extended period of limitation; and (3) refund of service tax paid on road construction, if the roads were exempt under Notification No. 25/2012-ST.
The Legal Issue
The central question was whether construction of internal roads within a privately owned industrial park, which are connected to and used by the general public, qualifies as a "road for use by general public" under Serial No. 13(a) of Notification No. 25/2012-ST, thereby exempting the service from service tax and disqualifying CENVAT credit.
Arguments Presented
For the Appellant
The appellant argued that the roads were internal infrastructure meant exclusively for users of the industrial park and not for the general public. It contended that since the land was privately owned and approved for industrial use, the roads could not be deemed public. It relied on the principle of double taxation, asserting that paying service tax and then being denied CENVAT credit amounted to unfair double burden. It further argued there was no suppression of facts, as all transactions were disclosed in books, and therefore the extended period of limitation under Section 73(2) could not apply.
For the Respondent
The Revenue contended that the roads, despite being within a private park, were functionally integrated into the public road network as per the Jaipur Master Plan. It argued that physical access by the public, coupled with connectivity to public roads, rendered them roads "for use by general public" under the notification. It relied on the literal interpretation of "public" and cited Paramount Infraventures Pvt. Ltd. to emphasize that mere physical access is insufficient; the right of access is the decisive factor.
The Court's Analysis
The Tribunal examined the definition of "public road" under the Motor Vehicles Act and dictionary sources, noting that "public place" requires not merely access but a right of access. It distinguished the Paramount Infraventures case, where a Formula One race track was held not to be a public road because access was restricted by ticketing and security, whereas in the present case, the roads in SIP-II were physically connected to public thoroughfares and served as transit routes for non-residents.
"The fact that roads in question are for the utility of the general public the same would fall within the scope of the exemption Notification No.25/2012-ST dated June 20, 2012 and as per S.No.13(a) services provided by way of construction... of road... for use by general public is exempt from the payment of service tax."
The Tribunal held that the appellant’s belief that the roads were private did not negate the objective reality of public use. It further observed that the Revenue’s invocation of the extended period of limitation was unjustified, as the appellant had not suppressed facts - it had paid service tax in good faith, believing the roads were private. Had the Revenue’s interpretation been correct, the appellant would have been entitled to a refund of the tax paid, making the transaction revenue-neutral.
The Tribunal emphasized that the issue was one of statutory interpretation, not fraud or concealment, and therefore the extended period under Section 73(2) could not be invoked.
The Verdict
The appellant succeeded in part. The Tribunal upheld the finding that the roads qualified as public roads under Serial No. 13(a) of Notification No. 25/2012-ST, rendering the service exempt from service tax. Consequently, the CENVAT credit of Rs. 35,50,371/- was disallowed. However, the Tribunal set aside the invocation of the extended period of limitation and remanded the matter to the adjudicating authority for recalculation of the refund of service tax paid during the normal period (April 2015 to June 2017), along with interest and appropriate penalty under Section 78 for the normal period. The appellant is entitled to refund of service tax paid during that period.
What This Means For Similar Cases
Public Access Trumps Private Ownership
- Practitioners must assess whether infrastructure within private developments is functionally integrated into the public road network, regardless of land ownership.
- Connectivity to public roads, inclusion in master plans, and actual public usage are decisive factors, not mere labels like "internal road."
CENVAT Credit Eligibility Turns on Exemption Status
- If a service qualifies for exemption under Notification 25/2012-ST, CENVAT credit is automatically disallowed under Rule 6 of CENVAT Credit Rules, 2004 - even if the taxpayer mistakenly paid tax.
- Taxpayers who paid tax in error may now claim refund, making the transaction revenue-neutral.
Extended Period of Limitation Requires Bad Faith
-
Mere misinterpretation of law, without concealment or suppression, cannot justify invoking the extended period under Section 73(2).
-
Good faith payment of tax, even if later found to be erroneous, precludes penalty and extended limitation.
-
Always document public access patterns and connectivity in project approvals.
-
Review all infrastructure projects for potential exemption under Notification 25/2012-ST before claiming CENVAT credit.
-
If tax was paid on exempt services, file refund claims proactively to avoid future disputes.