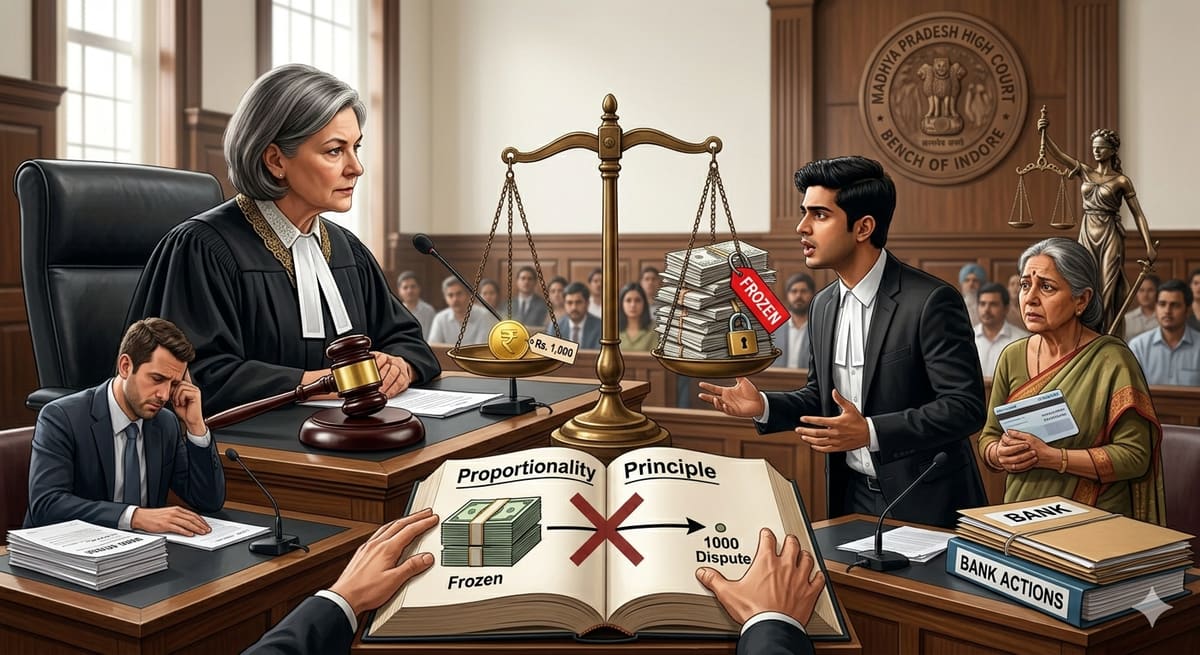
The Madhya Pradesh High Court has clarified that financial institutions cannot freeze entire bank accounts based on unverified allegations of cyber fraud involving minimal disputed sums. This ruling reinforces the principle that disproportionate action against account holders violates fundamental rights to property and access to financial services.
Background & Facts
The Dispute
The petitioner, Vinod Jat, held a savings bank account with Utkarsh Small Finance Bank Ltd. (Respondent No.2), Account No.1586019644771711, IFSC UTKS0001586, at its Indore Phooti Kothi Road Branch. On 06.03.2026, Respondent No.3 (a cyber crime agency) communicated to the bank that an amount of Rs.1,000/- credited to the petitioner’s account was suspected to be proceeds of cyber fraud. Based solely on this communication, the bank froze the entire account, which contained a balance of Rs.2,09,931/-. The petitioner had no prior notice, opportunity to be heard, or formal complaint filed against him.
Key Facts
The disputed amount was Rs.1,000/-, as specified in Annexure P/2 dated 06.03.2026
The total account balance at the time of freezing was Rs.2,09,931/-
The petitioner was not given any opportunity to explain the credit or contest the allegation
No FIR, charge sheet, or judicial order preceded the freezing
The bank acted on an email communication from a cyber crime cell without independent verification
The petitioner’s digital banking services (UPI, NEFT, RTGS) were also disabled
Procedural History
06.03.2026: Cyber crime agency communicated dispute of Rs.1,000/- to Utkarsh Small Finance Bank
07.03.2026: Bank froze entire account of Rs.2,09,931/- and disabled digital services
13.03.2026: Petitioner filed complaint with bank seeking unfreezing; no response received
14.03.2026: High Court issued interim directions in WP No.1100/2024 and WP No.1185/2024 permitting monthly withdrawals of Rs.50,000/- from frozen accounts pending investigation
16.04.2026: Petitioner filed Writ Petition No.16401/2026 under Article 226
06.05.2026: Hearing conducted before Justice Jai Kumar Pillai
The Parties' Positions
Petitioner: Argued that freezing the entire account was arbitrary, disproportionate, and violative of Article 14 and Article 21 of the Constitution. He submitted that the disputed amount was negligible compared to the total balance and that no judicial authority had authorized the freeze. He relied on the Court’s earlier interim order in WP No.1185/2024 as binding precedent.
Respondent Bank: Contended that it was bound by directives from law enforcement agencies under Section 102 of the CrPC and had no discretion to ignore such communications. It claimed compliance with regulatory obligations under RBI guidelines.
Relief Sought
The petitioner sought:
Immediate unfreezing of his savings account
Retention of only Rs.1,000/- in a fixed deposit or lien account pending judicial determination
Restoration of all digital banking services (UPI, NEFT, RTGS)
Any other relief deemed just by the Court
The Legal Issue
The central question was whether a bank may freeze an entire account based solely on an unverified cyber crime alert involving a minimal disputed amount, without any judicial order or due process, and whether such action violates constitutional rights under Article 14 and Article 21.
Arguments Presented
For the Petitioner
The petitioner relied on the Court’s own interim order dated 14.03.2024 in WP No.1185/2024, which permitted account holders to withdraw Rs.50,000/- monthly despite cyber crime allegations. He argued that freezing entire balances for minor disputes was manifestly unreasonable and disproportionate. He cited K.S. Puttaswamy v. Union of India to emphasize that financial autonomy is integral to personal liberty. He further contended that Section 102 CrPC permits seizure only of specific property, not entire accounts, and requires a magistrate’s order.
For the Respondent
The bank argued that it was obligated under RBI’s circulars and the Prevention of Money Laundering Act to act on alerts from law enforcement. It claimed that non-compliance could expose it to regulatory penalties and liability for facilitating illicit transactions. It asserted that the freeze was a precautionary measure, not punitive, and that it had no authority to question the credibility of police communications.
The Court's Analysis
The Court observed that while banks must cooperate with law enforcement, they cannot act as agents of extrajudicial enforcement. The Court noted that Section 102 CrPC authorizes seizure of property only upon a magistrate’s order, and mere communication from a cyber crime cell does not constitute such authorization. The Court emphasized that freezing an entire account of over Rs.2 lakh over a disputed Rs.1,000/- was grossly disproportionate and violated the principle of proportionality under Article 14.
"The bank’s action, though perhaps well-intentioned, has inflicted severe hardship on the petitioner, who has no control over the source of the credit, and has no recourse but to approach this Court for relief. The law does not permit such draconian measures on the basis of unverified allegations."
The Court further criticized the inaction of cyber crime cells across states, noting that while they issued freezing requests, they failed to respond to court communications, indicating systemic negligence. The Court held that the bank’s duty to comply with law enforcement does not override its obligation to protect customers’ fundamental rights.
The Verdict
The petition was allowed. The Court directed Utkarsh Small Finance Bank Ltd. to unfreeze the petitioner’s account within seven working days, retaining only Rs.1,000/- in a fixed deposit or lien account, subject to further orders of a competent Judicial Magistrate. All digital banking services, including UPI, NEFT, and RTGS, were ordered restored immediately. The Court directed that if no judicial order is passed within three months, the Rs.1,000/- shall be released to the petitioner upon intimation to the cyber crime agency.
What This Means For Similar Cases
Account Freezing Must Be Proportionate
Banks cannot freeze entire accounts based on unverified cyber crime alerts involving minor amounts
Only the disputed sum may be held in lien or fixed deposit pending judicial determination
Total account freezes require a magistrate’s order under Section 102 CrPC or equivalent judicial sanction
Due Process Is Non-Negotiable
Customers must be given notice and opportunity to respond before any restriction on account access
Banks must distinguish between regulatory alerts and judicial orders
Failure to follow due process exposes banks to constitutional liability under Article 21
Cyber Crime Agencies Must Act Responsibly
Law enforcement agencies cannot rely on email communications to trigger financial freezes
They must follow due process and respond to court directives within stipulated timelines
Non-compliance may result in contempt proceedings or administrative action