Case Law Analysis
|Income Tax Appellate Tribunal
Section 80-IB(10) | Minimum One-Acre Plot Must Be Exclusively Dedicated to Housing Project, Excluding Personal Residence: ITAT Cochin
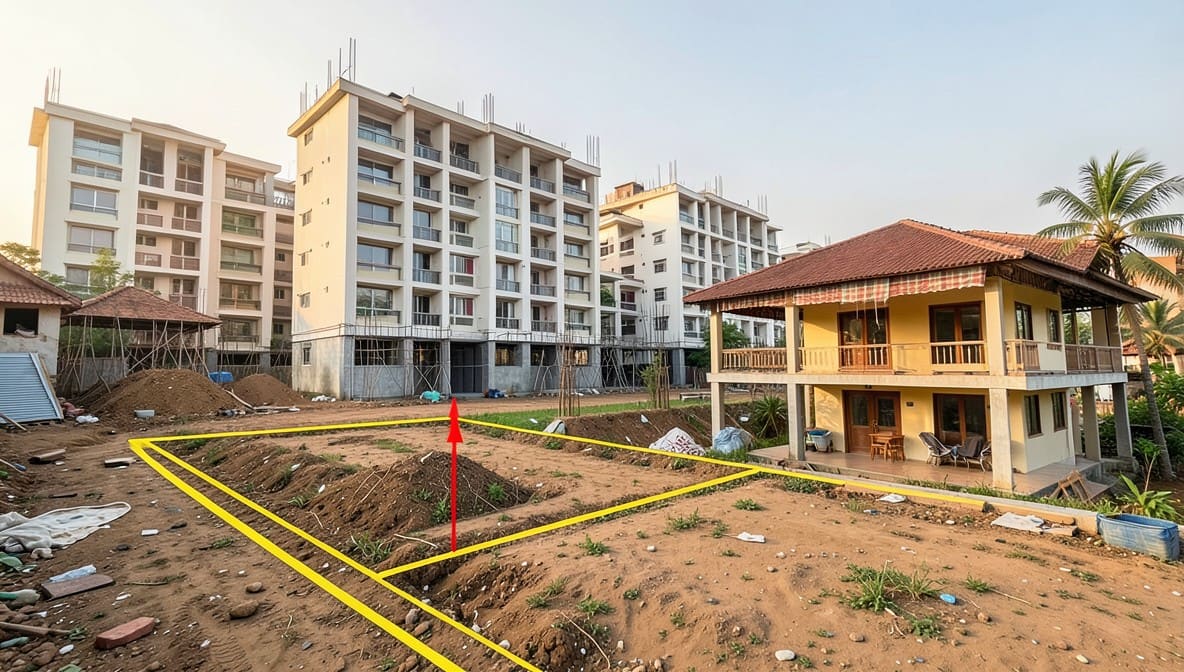
The ITAT Cochin has ruled that to claim deduction under Section 80-IB(10), a housing project must be developed on a plot of at least one acre, with no portion allocated to personal residence or non-housing structures. This clarifies a critical eligibility criterion for developers seeking tax incentives, impacting project planning and land consolidation strategies across residential real estate.