Topic

section 143(2)

Section 143(2) of the Income Tax Act, 1961, mandates that a notice be issued by a jurisdictional Assessing Officer before initiating a scrutiny assessment of a taxpayer's return.

9 articlesLatest July 2026
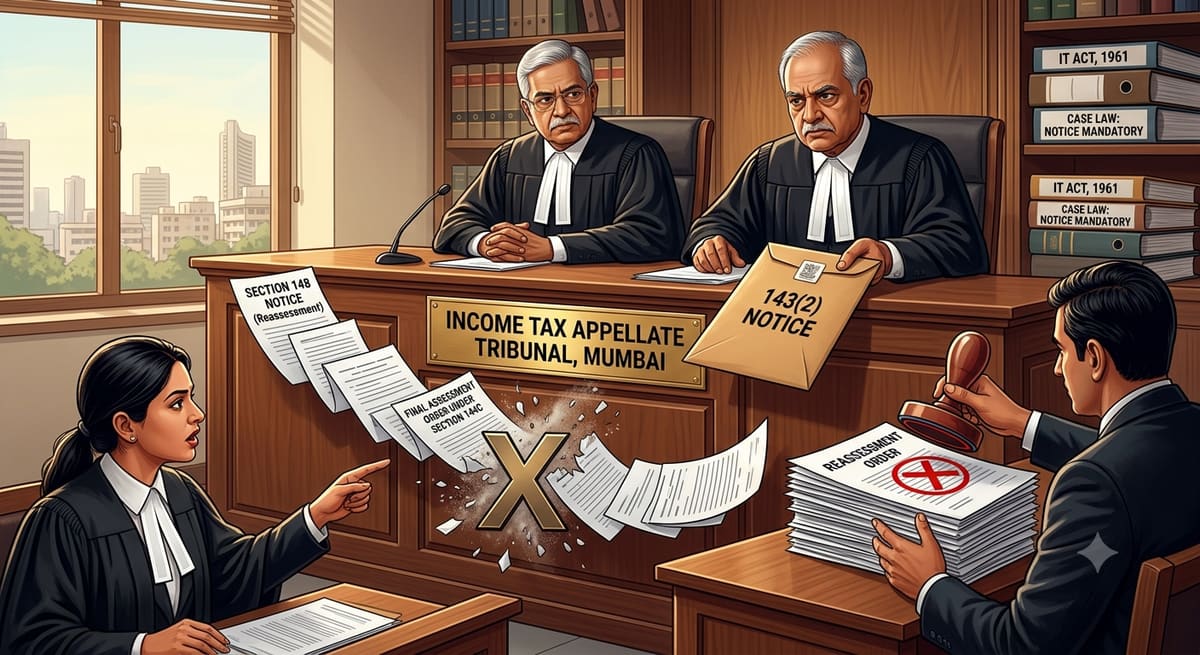
Section 143(2) Notice Mandatory for Reassessment | Non-Compliance Vitiates Assessment Under Section 144C : ITAT Mumbai
Case Law Analysis
|Income Tax Appellate Tribunal

Section 143(2) Notice Mandatory for Reassessment | Non-Compliance Vitiates Assessment Under Section 144C : ITAT Mumbai

ITAT Mumbai rules that failure to issue a mandatory notice under Section 143(2) during reassessment proceedings renders the entire assessment void ab initio. The tribunal held that issuing a demand notice alongside a draft assessment order under Section 144C without adhering to procedural safeguards constitutes a jurisdictional error, impacting all taxpayers undergoing reassessment.

Section 143(2) IT Act | Non-Issuance of Notice Vitiates Reassessment; Section 292BB Cannot Cure Jurisdictional Defect : ITAT Kolkata
Case Law Analysis
|Income Tax Appellate Tribunal

Section 143(2) IT Act | Non-Issuance of Notice Vitiates Reassessment; Section 292BB Cannot Cure Jurisdictional Defect : ITAT Kolkata

The ITAT Kolkata has ruled that failure to issue a Section 143(2) notice at all renders reassessment proceedings null and void, and the curative provision under Section 292BB does not apply to complete non-issuance - only defective service. This clarifies a critical jurisdictional safeguard for assessees, reinforcing that procedural compliance is non-negotiable in tax reassessments.

Section 143(2) Income Tax Act | Assessment Void if AO Lacks Pecuniary Jurisdiction Under CBDT Instruction No. 1/2011: ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 143(2) Income Tax Act | Assessment Void if AO Lacks Pecuniary Jurisdiction Under CBDT Instruction No. 1/2011: ITAT Delhi

ITAT Delhi has ruled that an income tax assessment under Section 143(3) is legally invalid if the notice under Section 143(2) was issued by an Assessing Officer without proper pecuniary jurisdiction, as mandated by CBDT Instruction No. 1/2011. This sets a critical precedent for taxpayers and tax officers alike - jurisdictional compliance is not procedural but jurisdictional, and defects here cannot be cured by subsequent actions.

Section 69A IT Act | Cash Deposits During Demonetization Require Strict Documentary Proof of Source: ITAT Jodhpur Remands Case for Fresh Assessment
|Income Tax Appellate Tribunal

Section 69A IT Act | Cash Deposits During Demonetization Require Strict Documentary Proof of Source: ITAT Jodhpur Remands Case for Fresh Assessment

ITAT Jodhpur rules that cash deposits during demonetization under Section 69A of the Income Tax Act demand rigorous documentary proof of source. The Tribunal remanded the case for fresh assessment, emphasizing procedural compliance and the assessee’s burden to substantiate transactions with valid evidence, impacting tax litigation and banking law.

Section 263 ITA | No Fresh Section 143(2) Notice Required for Revisionary Assessments After PCIT Set-Aside : ITAT Bangalore
Case Law Analysis
|Income Tax Appellate Tribunal

Section 263 ITA | No Fresh Section 143(2) Notice Required for Revisionary Assessments After PCIT Set-Aside : ITAT Bangalore

ITAT Bangalore clarifies that reassessment under Section 263 of the Income Tax Act does not necessitate a fresh notice under Section 143(2), as the proceedings are a continuation of the original assessment. This ruling streamlines procedural compliance for tax authorities and assessees, avoiding redundant notices in set-aside cases.

Section 143(2) IT Act | Notice Issued by Non-Jurisdictional AO Voids Assessment Ab Initio : ITAT Delhi Follows CBDT Instruction No. 1/2011
Case Law Analysis
|Income Tax Appellate Tribunal

Section 143(2) IT Act | Notice Issued by Non-Jurisdictional AO Voids Assessment Ab Initio : ITAT Delhi Follows CBDT Instruction No. 1/2011

ITAT Delhi rules that an assessment order is void ab initio if the notice under Section 143(2) is issued by an Assessing Officer lacking pecuniary jurisdiction, as mandated by CBDT Instruction No. 1/2011. The ruling reinforces jurisdictional compliance as a non-negotiable prerequisite for valid tax assessments, impacting all pending and future scrutiny cases.

Section 143(2) IT Act | Mandatory Notice Non-Issuance Voids Scrutiny Assessment Even for Delayed Returns : ITAT Lucknow
Case Law Analysis
|Income Tax Appellate Tribunal

Section 143(2) IT Act | Mandatory Notice Non-Issuance Voids Scrutiny Assessment Even for Delayed Returns : ITAT Lucknow

ITAT Lucknow quashes an assessment order for failure to issue the mandatory Section 143(2) notice, reinforcing that jurisdictional compliance is non-negotiable regardless of return filing timelines. The ruling underscores that procedural lapses render assessments void ab initio, impacting taxpayers facing re-assessment proceedings.

Section 144B | Jurisdictional AO’s Section 143(2) Notice Valid Before Faceless Assessment: ITAT Mumbai Upholds Procedural Compliance
Case Law Analysis
|Income Tax Appellate Tribunal

Section 144B | Jurisdictional AO’s Section 143(2) Notice Valid Before Faceless Assessment: ITAT Mumbai Upholds Procedural Compliance

ITAT Mumbai rules that the issuance of a Section 143(2) notice by the Jurisdictional Assessing Officer does not invalidate a faceless assessment under Section 144B. The Tribunal remanded the case for fresh adjudication on merits, reinforcing that procedural compliance under faceless assessment regimes does not override jurisdictional authority. This ruling clarifies the interplay between jurisdictional notices and faceless assessment procedures, impacting tax assessees and revenue authorities alike.