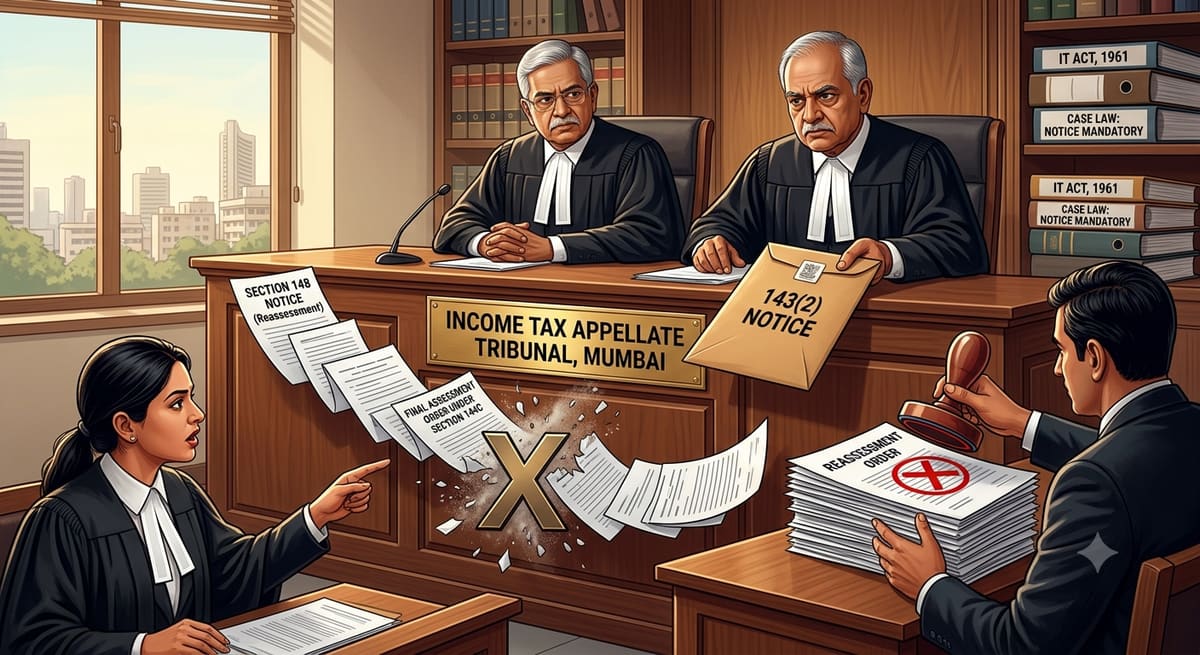
The Income Tax Appellate Tribunal, Mumbai, has clarified that a reassessment completed under the faceless regime does not become invalid merely because the mandatory notice under section 143(2) was issued by the Jurisdictional Assessing Officer rather than the Faceless Assessment Unit. While upholding the legal validity of the assessment, the Tribunal set aside the substantive additions on merits and remanded the case for fresh adjudication, emphasizing procedural fairness.
Background & Facts
The Dispute
The assessee, Arham Anmol Projects Private Limited, is a company engaged in renting and maintaining immovable property and providing construction services. It did not file its original return of income for Assessment Year 2019-20. Information available on the Insight Portal revealed financial transactions aggregating to Rs. 2,94,31,158, prompting the issuance of a notice under section 148 on 27.03.2023. The assessee filed a return on 26.04.2023 declaring income of Rs. 58,16,560. Subsequent statutory notices under sections 142(1) and 143(2) were issued, but the assessee failed to provide substantive replies or documentary evidence. The assessment was completed under section 147 read with section 144B, resulting in substantial additions.
Key Facts
- The assessee’s return was filed on 26.04.2023 in response to notice under section 148 dated 27.03.2023
- Notice under section 143(2) was issued by the Jurisdictional Assessing Officer, ACIT, Circle-1, Kalyan
- The assessment order dated 21.02.2024 was framed by the Assessment Unit under the Faceless Scheme
- The Assessing Officer made the following additions:
- Short Term Capital Gain: Rs. 4,54,49,186 (cost of acquisition assumed Nil)
- Contract receipts: Rs. 7,68,674 (12% of Rs. 64,05,620 under section 194C)
- Professional fees: Rs. 2,07,865 (50% of Rs. 4,15,730)
- Rent receipts: Rs. 2,00,25,538 (treated as business income)
- Total assessed income: Rs. 7,22,67,823
- Penalty proceedings initiated under sections 270A and 272A(1)(d)
- Interest and fee levied under sections 234A, 234B, 234C, and 234F
Procedural History
- 27.03.2023: Notice under section 148 issued
- 26.04.2023: Return filed declaring income of Rs. 58,16,560
- 21.02.2024: Assessment completed under section 147 read with section 144B
- 18.06.2025: CIT(A) dismissed appeal, sustaining all additions
- 28.01.2026: Hearing before ITAT Mumbai
- 26.03.2026: Judgment pronounced
The Parties' Positions
For the Assessee:
- Contended that the assessment is invalid because the notice under section 143(2) was issued by the Jurisdictional Assessing Officer, while the assessment was completed by the Faceless Assessment Unit
- Argued that section 144B requires the same officer to issue notice and complete assessment
- Invoked Hexaware Technologies Ltd. v. ACIT to assert exclusivity of faceless machinery for notice issuance
- Claimed non-compliance was due to extraordinary circumstances: multiple civil, criminal, and regulatory proceedings; freezing of bank accounts; and directorial disputes
- Sought admission of additional evidence not filed before lower authorities
For the Revenue:
- Contended that notice under section 143(2) was duly issued by the Jurisdictional Assessing Officer and served on the assessee
- Relied on Inder Dev Gupta v. ACIT and T.K.S. Builders (P.) Ltd. to establish concurrent jurisdiction between Jurisdictional and Faceless Assessing Officers
- Argued that section 144B is procedural and does not extinguish the jurisdiction of the Jurisdictional Assessing Officer under section 120
- Highlighted retrospective deletion of sub-section (9) of section 144B as legislative intent to avoid invalidation on technical grounds
- Maintained that section 292BB is not applicable as the notice was issued, not merely defective in service
Relief Sought
The assessee sought:
- Quashing of the assessment order dated 21.02.2024
- Setting aside of the CIT(A) order dated 18.06.2025
- Cancellation of all additions and penalties
- Admission of additional evidence
- Relief from interest and penalty under sections 234A, 234B, 234C, 234F, 270A, and 272A(1)(d)
The Legal Issue
The central question was whether the issuance of a notice under section 143(2) by the Jurisdictional Assessing Officer, followed by completion of assessment by the Faceless Assessment Unit under section 144B, vitiates the assessment on grounds of jurisdictional infirmity.
Arguments Presented
For the Appellant/Petitioner
The learned Authorized Representative contended that the bifurcation between issuance of notice and completion of assessment renders the proceedings invalid. Relying on Hexaware Technologies Ltd. v. ACIT, the assessee argued that the faceless scheme under section 151A mandates exclusive allocation of powers to the Faceless Assessment Unit, and any deviation by the Jurisdictional Assessing Officer nullifies jurisdiction. It was further submitted that section 292BB cannot cure a foundational defect in issuance of notice, and that the deletion of sub-section (9) of section 144B does not validate non-compliance with mandatory procedural requirements. The non-appearance before lower authorities, the AR submitted, was due to circumstances beyond control, including litigation, freezing of accounts, and administrative paralysis.
For the Respondent/State
The Departmental Representative countered that the notice under section 143(2) was validly issued by the Jurisdictional Assessing Officer, who retains concurrent jurisdiction under section 120(5) and notifications issued by the CBDT. Citing Inder Dev Gupta v. ACIT and T.K.S. Builders (P.) Ltd., the DR emphasized that section 144B is procedural and does not create a separate class of Assessing Officer. The statutory framework permits functional allocation without extinguishing jurisdiction. The deletion of sub-section (9) of section 144B, the DR argued, reflects legislative intent to prevent technical invalidation where jurisdictional requirements are met. The notice was issued, served, and acknowledged; hence, no defect exists to be cured.
The Court's Analysis
The Tribunal undertook a detailed examination of the statutory architecture governing faceless assessment under section 144B and the concurrent jurisdictional framework under sections 120 and 127. It distinguished the facts of Hexaware Technologies Ltd. from the present case, noting that Hexaware dealt with the validity of notice under section 148 issued by the Jurisdictional Assessing Officer contrary to the automated allocation mandate under section 151A. In contrast, the present case involved a notice under section 143(2), issued after the return was filed and prior to assessment completion.
"The law does not mandate that the officer completing the assessment must necessarily be the same officer who issued the notice under section 143(2). The bifurcation of stages between issuance of notice and completion of assessment is inherent in the statutory design of the faceless regime."
The Tribunal held that section 144B regulates the manner of assessment, not the source of jurisdiction. The Jurisdictional Assessing Officer retains authority to issue notices under section 143(2), and the Faceless Assessment Unit is empowered to complete the assessment without re-issuing the notice. The deletion of sub-section (9) of section 144B, which previously allowed invalidation for procedural lapses, was interpreted as legislative intent to prevent hyper-technical challenges where jurisdictional requirements are satisfied.
The Tribunal further relied on the Delhi High Court’s reasoning in T.K.S. Builders (P.) Ltd., which held that the faceless scheme operates in tandem with the existing jurisdictional framework. The Court observed that the use of the term "concurrently" in the notifications indicates coexistence, not exclusion. The Tribunal concluded that the issuance of section 143(2) notice by a competent Jurisdictional Assessing Officer satisfies the mandatory jurisdictional requirement, and completion of assessment by the Faceless Unit does not vitiate the proceedings.
However, on the merits, the Tribunal found the additions to be mechanically arrived at. The Assessing Officer treated entire sale consideration as capital gain without examining cost of acquisition, period of holding, or indexed cost under sections 45 and 48. The estimation of income at 12% and 50% on gross receipts was done without verifying books of account or reconciling with ITS data. The CIT(A) had merely confirmed these additions without independent scrutiny. The Tribunal held that the assessee’s failure to respond earlier did not justify mechanical assumptions by the tax authority. In the interest of justice, the matter was remanded for fresh adjudication.
The Verdict
The appeal was partly allowed. The legal ground challenging the validity of the assessment under section 144B was dismissed. However, the additions of Rs. 4,54,49,186 (STCG), Rs. 7,68,674 (contract receipts), Rs. 2,07,865 (professional fees), and Rs. 2,00,25,538 (rent receipts) were set aside and restored to the file of the Assessing Officer for fresh adjudication. The Assessing Officer is directed to re-examine the case after affording the assessee a reasonable opportunity to submit documentary evidence, including purchase deeds, cost computation, and reconciliation of receipts. The assessee must cooperate fully and avoid unwarranted adjournments. In case of non-compliance, the Assessing Officer may proceed ex parte. The penalty and interest proceedings are to be reconsidered in light of the fresh assessment.
What This Means For Similar Cases
Notice Under Section 143(2) Is Valid If Issued by Jurisdictional AO
- Practitioners must now recognize that notices under section 143(2) issued by the Jurisdictional Assessing Officer remain valid even if the assessment is completed by a Faceless Unit
- Challenges based on bifurcation of notice issuance and assessment completion are legally unsustainable
- The burden shifts to the assessee to prove that the notice was not issued or was invalid, not merely that a different officer completed the assessment
Faceless Assessment Does Not Erase Pre-Assessment Jurisdiction
- Section 144B is procedural, not substantive; it does not override the jurisdiction conferred under section 120
- Jurisdictional Assessing Officers retain authority to issue notices under sections 148 and 143(2) even after the faceless regime
- Tax authorities must ensure notices are issued by competent officers, but need not re-issue them if already validly served
Merits Require Substantive Examination, Not Mechanical Additions
- Mechanical assumptions of Nil cost or arbitrary profit percentages are impermissible
- Assessing Officers must verify books of account, reconcile with ITS data, and consider nature of asset and holding period before applying section 45 and 48
- Failure to discharge the burden of proof by the assessee does not absolve the tax authority of its duty to conduct a fair and reasoned assessment
- Remand for fresh adjudication is appropriate where additions are based on incomplete or speculative reasoning