Topic

penalty imposition

Penalty imposition in Indian law refers to financial sanctions levied by authorities under specific statutes like the RTI Act, Income Tax Act, or Customs Act, requiring proof of intent, default, or violation beyond mere procedural lapses.

15 articlesLatest June 2026
Inadvertent Alteration & Proportionality | Penalty Imposed But Seal Must Be Removed Pending Compounding: MP HC Gwalior
Case Law Analysis
|Madhya Pradesh High Court

Inadvertent Alteration & Proportionality | Penalty Imposed But Seal Must Be Removed Pending Compounding: MP HC Gwalior

The Madhya Pradesh High Court ruled that an inadvertent, bona fide shop alteration by a lessee does not bar compounding of the violation - while the penalty must be paid, the municipal seal must be lifted immediately to restore livelihood rights. This affirms that administrative penalties must yield to the constitutional right to trade when no malice or intent to evade law exists, setting a critical precedent for small traders facing rigid municipal enforcement.
Abetment Under Customs Act Requires Identified Principal Offender | Penalty Set Aside When Importer Untraceable : CESTAT Chennai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Abetment Under Customs Act Requires Identified Principal Offender | Penalty Set Aside When Importer Untraceable : CESTAT Chennai

CESTAT Chennai has ruled that penalty for abetment under Section 112(a) of the Customs Act cannot be imposed without identifying the actual importer as the principal offender. This reinforces natural justice in customs enforcement, protecting intermediaries from vicarious liability when the true violator remains unknown, and sets a precedent for fair penalty imposition in smuggling cases.

Section 112(b) Customs Act | Penalty Quashed Absent Proof of Knowledge or Physical Possession of Contraband : CESTAT
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Section 112(b) Customs Act | Penalty Quashed Absent Proof of Knowledge or Physical Possession of Contraband : CESTAT

CESTAT rules that penalties under Section 112(b) of the Customs Act cannot be imposed without concrete evidence of the appellant's knowledge or physical possession of illicit goods. The tribunal underscores that mere association with a supplier or failure to prove mens rea invalidates penalty imposition, reinforcing natural justice principles in customs enforcement.

SEZ Act Section 26(1)(e) | Customs Duty Exemption for SEZ Supplies Mandatory; Penalty Quashed for Violating Natural Justice : CESTAT
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

SEZ Act Section 26(1)(e) | Customs Duty Exemption for SEZ Supplies Mandatory; Penalty Quashed for Violating Natural Justice : CESTAT

CESTAT rules that supplies to SEZ units under Section 26(1)(e) of the SEZ Act are exempt from customs duty, and any penalty imposed without proper notice or evidence violates principles of natural justice. The tribunal set aside a ₹72 lakh demand, reinforcing that procedural fairness is non-negotiable in duty exemption cases affecting traders and SEZ operators.

Customs Act Section 28 | Penalty Invalid Without Corroborative Evidence of Involvement: CESTAT
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Customs Act Section 28 | Penalty Invalid Without Corroborative Evidence of Involvement: CESTAT

CESTAT quashes penalty against an NRI businessman, ruling that uncorroborated WhatsApp messages and retracted statements cannot substitute for tangible evidence of intent or participation in customs evasion. This reinforces that suspicion alone, however plausible, is legally insufficient under Section 28 - a critical safeguard for overseas traders and importers facing speculative enforcement.

Section 112(a) Customs Act | Penalty Not Imposable on Non-Importer Without Evidence of Collusion or Undervaluation : CESTAT
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Section 112(a) Customs Act | Penalty Not Imposable on Non-Importer Without Evidence of Collusion or Undervaluation : CESTAT

CESTAT quashed a ₹20 lakh penalty against a non-importer under Section 112(a) of the Customs Act, holding that mere association with an importer is insufficient to impose liability for undervaluation without proof of active participation, collusion, or intent. This clarifies the scope of personal liability for third parties in customs fraud cases, protecting innocent business associates from vicarious penalties.

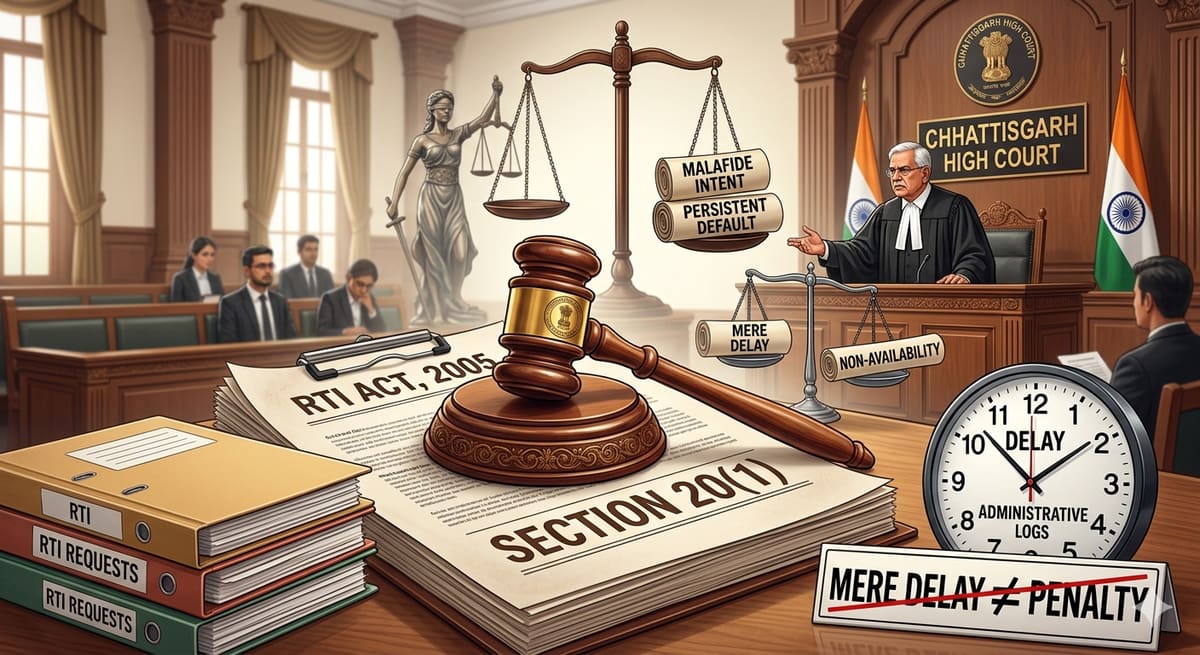
Section 20(1) RTI Act | Penalty Requires Proven Malafide Intent or Persistent Default, Not Mere Delay or Non-Availability : Chhattisgarh HC
Case Law Analysis
|Chhattisgarh High Court

Section 20(1) RTI Act | Penalty Requires Proven Malafide Intent or Persistent Default, Not Mere Delay or Non-Availability : Chhattisgarh HC

The Chhattisgarh High Court has ruled that Public Information Officers cannot be penalized under Section 20(1) of the RTI Act for mere delay or incomplete information unless there is a clear finding of malafide intent or persistent, unreasonable default. This sets a vital safeguard for PIOs acting in good faith and reinforces that procedural lapses alone do not justify financial penalties under the law.

Customs Act Sections 114(iii) & 114AA | Penalty Invalid Without Direct Evidence of Knowledge or Collusion in Fraudulent Export : CESTAT Kolkata
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Customs Act Sections 114(iii) & 114AA | Penalty Invalid Without Direct Evidence of Knowledge or Collusion in Fraudulent Export : CESTAT Kolkata

CESTAT Kolkata has ruled that penalties under Customs Act Sections 114(iii) and 114AA cannot be imposed on customs brokers without direct evidence linking them to the intent or active participation in fraudulent export schemes. This reinforces the principle that mere association with defaulting exporters is insufficient - the burden of proving collusion rests squarely on the Revenue, safeguarding brokers from speculative liability.

Section 271(1)(c) IT Act | Penalty Invalid Without Proven Concealment, Even for Estimated Additions : ITAT Mumbai
Case Law Analysis
|Income Tax Appellate Tribunal

Section 271(1)(c) IT Act | Penalty Invalid Without Proven Concealment, Even for Estimated Additions : ITAT Mumbai

ITAT Mumbai rules that penalty under Section 271(1)(c) cannot be imposed merely on estimated additions unless concealment of income is proven. The decision clarifies that additions based on gross profit rates or suspected accommodation entries do not meet the legal threshold for penalty, protecting taxpayers from arbitrary penal action.