Topic

Natural Justice in Tax Proceedings

6 articlesLatest July 2026
Section 270A IT Act | Penalty for Misreporting Requires Cogent Evidence of False Particulars : ITAT Ahmedabad
Case Law Analysis
|Income Tax Appellate Tribunal

Section 270A IT Act | Penalty for Misreporting Requires Cogent Evidence of False Particulars : ITAT Ahmedabad

ITAT Ahmedabad sets a precedent that penalties under Section 270A for misreporting income cannot be imposed without concrete proof of false particulars or deliberate suppression, even if a deduction is disallowed. This ruling reinforces natural justice principles, protecting taxpayers from arbitrary penalties based solely on disallowed claims.
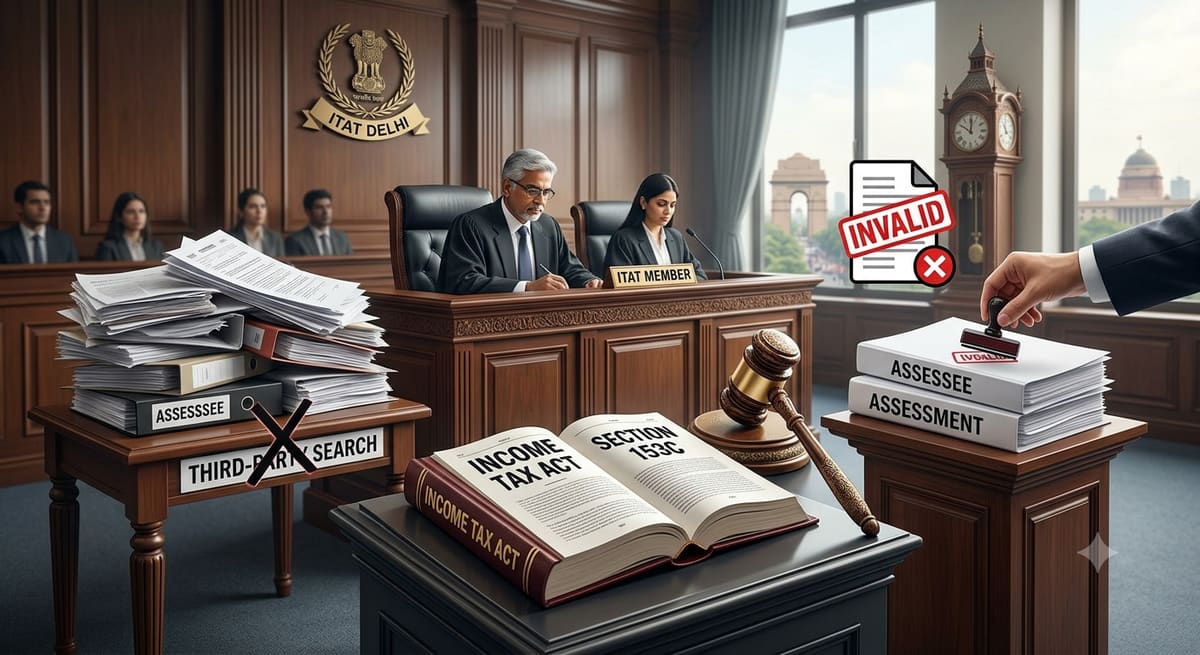
Section 153C Income Tax Act | Assessment Invalid Without Incriminating Material Belonging to Assessee Found During Third-Party Search : ITAT Delhi
Case Law Analysis
|Income Tax Appellate Tribunal

Section 153C Income Tax Act | Assessment Invalid Without Incriminating Material Belonging to Assessee Found During Third-Party Search : ITAT Delhi

The ITAT Delhi has ruled that an assessment under Section 153C cannot stand unless incriminating material directly belonging to the assessee is discovered during a search of a third party. This clarifies a critical jurisdictional limit on the tax department’s power to reassess unrelated taxpayers, reinforcing natural justice and statutory compliance in income tax proceedings.

Section 69 Income Tax Act | Unverified Third-Party Excel Data Insufficient for Unexplained Cash Addition Without Corroboration : ITAT Agra
|Income Tax Appellate Tribunal

Section 69 Income Tax Act | Unverified Third-Party Excel Data Insufficient for Unexplained Cash Addition Without Corroboration : ITAT Agra

ITAT Agra quashed a Rs.16.28 lakh addition under Section 69 after ruling that revenue cannot rely solely on unauthenticated Excel data from a third-party search without corroboration or opportunity for cross-examination. This reinforces that digital evidence, however voluminous, must meet basic standards of natural justice to justify tax additions - a critical safeguard for taxpayers facing algorithmic or bulk data-driven assessments.

Section 10(26) IT Act | Scheduled Tribe Exemption Does Not Excuse Unexplained Cash Deposits or Non-Filing of Returns : ITAT Guwahati
Case Law Analysis
|Income Tax Appellate Tribunal

Section 10(26) IT Act | Scheduled Tribe Exemption Does Not Excuse Unexplained Cash Deposits or Non-Filing of Returns : ITAT Guwahati

The ITAT Guwahati has ruled that eligibility for tax exemption under Section 10(26) for Scheduled Tribe members does not absolve them from proving the source of cash deposits or complying with mandatory return filing obligations. This sets a critical precedent: tax exemption and procedural compliance are distinct obligations, affecting thousands of tribal assessees who may mistakenly believe exemption removes all tax duties.