Topic

Input Service Distributor

3 articlesLatest July 2026
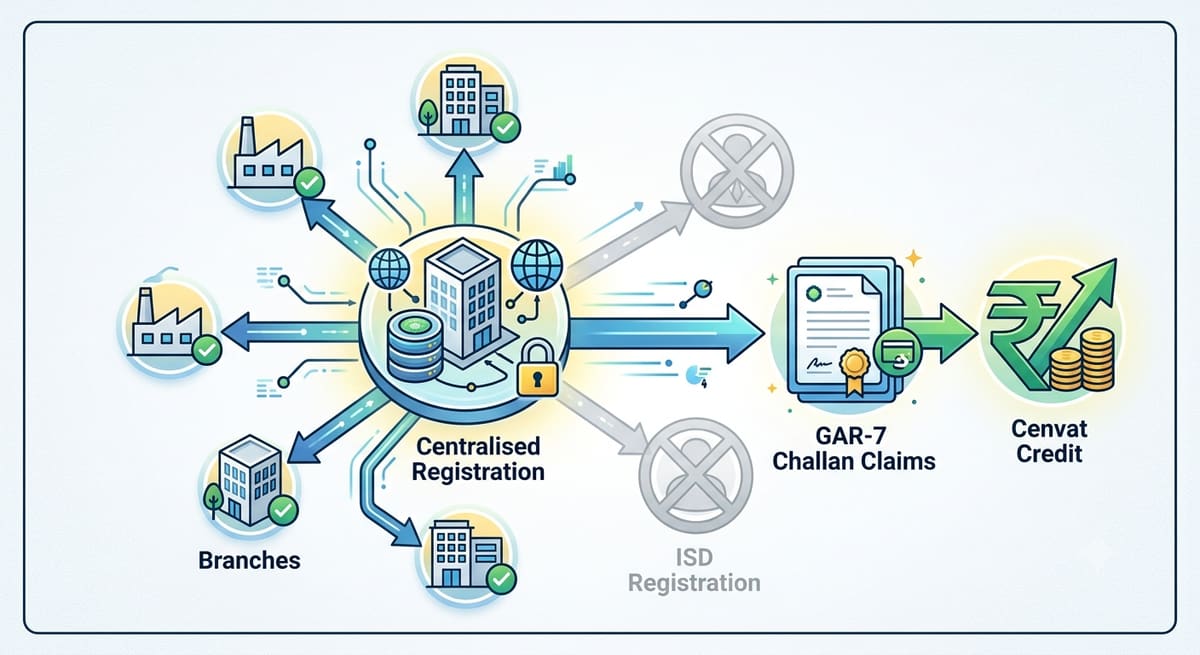
Cenvat Credit | Centralised Registration Allows GAR-7 Challan Claims Without ISD Registration: CESTAT Chandigarh
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Cenvat Credit | Centralised Registration Allows GAR-7 Challan Claims Without ISD Registration: CESTAT Chandigarh

Taxpayers with centralised registration can claim Cenvat credit using GAR-7 challans even without ISD registration, as CESTAT Chandigarh prioritises substantive entitlement over procedural compliance. This ruling empowers large multi-unit businesses to streamline input tax credit claims without the added burden of separate ISD setup, significantly reducing administrative friction under the erstwhile service tax regime.
CENVAT Credit on Leadership Fees in Consortium Projects Admissible if Not Exclusively for Exempt Activities | CESTAT Hyderabad
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

CENVAT Credit on Leadership Fees in Consortium Projects Admissible if Not Exclusively for Exempt Activities | CESTAT Hyderabad

CESTAT Hyderabad rules that service tax paid on leadership fees in consortium turnkey projects qualifies for CENVAT credit, provided the services are not exclusively linked to exempt manufacturing activities and tax was properly discharged under reverse charge. This clarifies the eligibility of indirect service costs in complex infrastructure contracts, impacting consortium-based EPC players nationwide.

Section 16(2) CGST Act | ITC Distribution by ISDs Valid Only After Statutory Conditions Met : Madras HC Strikes Down Forced Monthly Credit Allocation
Case Law Analysis
|Madras High Court

Section 16(2) CGST Act | ITC Distribution by ISDs Valid Only After Statutory Conditions Met : Madras HC Strikes Down Forced Monthly Credit Allocation

Madras High Court ruled that Input Service Distributors cannot distribute Input Tax Credit merely upon invoice receipt but must first satisfy all conditions under Section 16(2) of the CGST Act. The judgment invalidates Rule 39(1)(a) to the extent it mandates same-month distribution, protecting businesses from forced allocation of ineligible credit and ensuring compliance with statutory entitlement.