Topic

Export of Services

Export of services under Indian tax law refers to the supply of services to overseas recipients where payment is received in convertible foreign exchange, exempting such transactions from service tax or GST.

11 articlesLatest July 2026
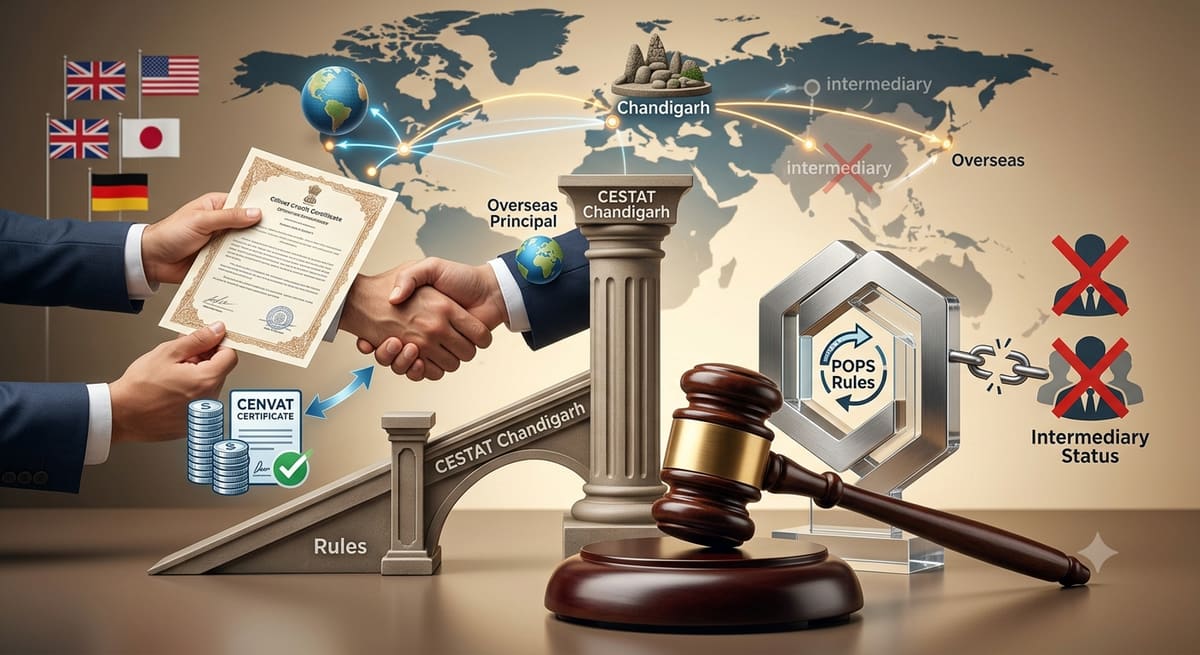
POPS Rules | Direct Contract with Overseas Principal Excludes Intermediary Status, Entitles Cenvat Credit: CESTAT Chandigarh
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

POPS Rules | Direct Contract with Overseas Principal Excludes Intermediary Status, Entitles Cenvat Credit: CESTAT Chandigarh

CESTAT Chandigarh rules that Genpact Services LLC, providing BPO services directly to an overseas principal under a single contract, does not qualify as an 'intermediary' under the Place of Provision of Services Rules. The ruling entitles the appellant to Cenvat credit refunds worth ₹14.55 crore, setting a precedent for service exporters with direct overseas contracts.
Service Tax on Export of Services | Recipient’s Location Outside India Determines Tax Exemption : CESTAT Kolkata
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Service Tax on Export of Services | Recipient’s Location Outside India Determines Tax Exemption : CESTAT Kolkata

CESTAT Kolkata rules that services rendered in India to a foreign recipient qualify as 'export of services' and are exempt from service tax if payment is received in foreign exchange. The ruling sets aside a ₹4.55 crore tax demand, reinforcing that taxability hinges on the recipient’s location, not the place of performance.

Rule 5 Cenvat Credit Rules, 2004 | Limitation for Refund of Unutilized Credit on Export of Services Begins at End of Quarter Upon FIRC Receipt : CESTAT Chennai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Rule 5 Cenvat Credit Rules, 2004 | Limitation for Refund of Unutilized Credit on Export of Services Begins at End of Quarter Upon FIRC Receipt : CESTAT Chennai

CESTAT Chennai rules that for refund claims under Rule 5 of the Cenvat Credit Rules, the one-year limitation period under Section 11B of the Central Excise Act starts from the end of the quarter in which the Foreign Inward Remittance Certificate is received, not the invoice date. This clarifies a critical timing ambiguity for exporters and service providers claiming Cenvat credit refunds, ensuring compliance aligns with actual receipt of foreign payment.

Cenvat Credit Rules Rule 9 | No Registration Required to Claim Input Service Credit for Exported Services : CESTAT Hyderabad
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Cenvat Credit Rules Rule 9 | No Registration Required to Claim Input Service Credit for Exported Services : CESTAT Hyderabad

CESTAT Hyderabad rules that service tax registration is not a prerequisite for availing Cenvat credit on input services used to export services, even if registration was obtained retroactively. This empowers exporters who delayed registration but used eligible input services during the export period, clarifying a critical compliance gap in service tax refund claims.

Service Tax on Outbound Tours | 'Tour Operator Service' to Indian Tourists Taxable Pre-Negative List Regime: CESTAT Bangalore
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Service Tax on Outbound Tours | 'Tour Operator Service' to Indian Tourists Taxable Pre-Negative List Regime: CESTAT Bangalore

CESTAT Bangalore rules that outbound tour services provided by Indian operators to Indian tourists were taxable under the Service Tax regime prior to the Negative List introduction, rejecting the 'export of services' claim. The ruling clarifies territorial applicability of taxable services, impacting tour operators' compliance obligations for pre-2012 periods.

Section 65(105)(zzb) Finance Act | Reimbursement of Joint Advertising Costs Between Group Companies Not Taxable as Business Auxiliary Service : CESTAT Chennai
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Section 65(105)(zzb) Finance Act | Reimbursement of Joint Advertising Costs Between Group Companies Not Taxable as Business Auxiliary Service : CESTAT Chennai

CESTAT Chennai rules that reimbursement of shared advertising expenses between group companies does not qualify as 'Business Auxiliary Service' under Section 65(105)(zzb) of the Finance Act, 1994, in the absence of a client-provider relationship. The ruling clarifies that cost-sharing arrangements for business promotion are not taxable unless a distinct service is rendered to a specific client, impacting multinational corporations and group entities engaged in joint marketing.

Rule 3(2) Export of Service Rules | 'Effective Use' by Overseas Recipient Suffices for Export Rebate : CESTAT Chandigarh
Case Law Analysis
|Custom, Excise & Service Tax Tribunal

Rule 3(2) Export of Service Rules | 'Effective Use' by Overseas Recipient Suffices for Export Rebate : CESTAT Chandigarh

CESTAT Chandigarh clarifies that call center services qualify as 'export of services' under Rule 3(2) of the Export of Service Rules, 2005 if the overseas recipient effectively uses them, entitling service providers to rebate claims. The ruling rejects the Revenue's argument that physical performance in India disqualifies export status, reinforcing the 'effective use' doctrine for cross-border service tax exemptions.