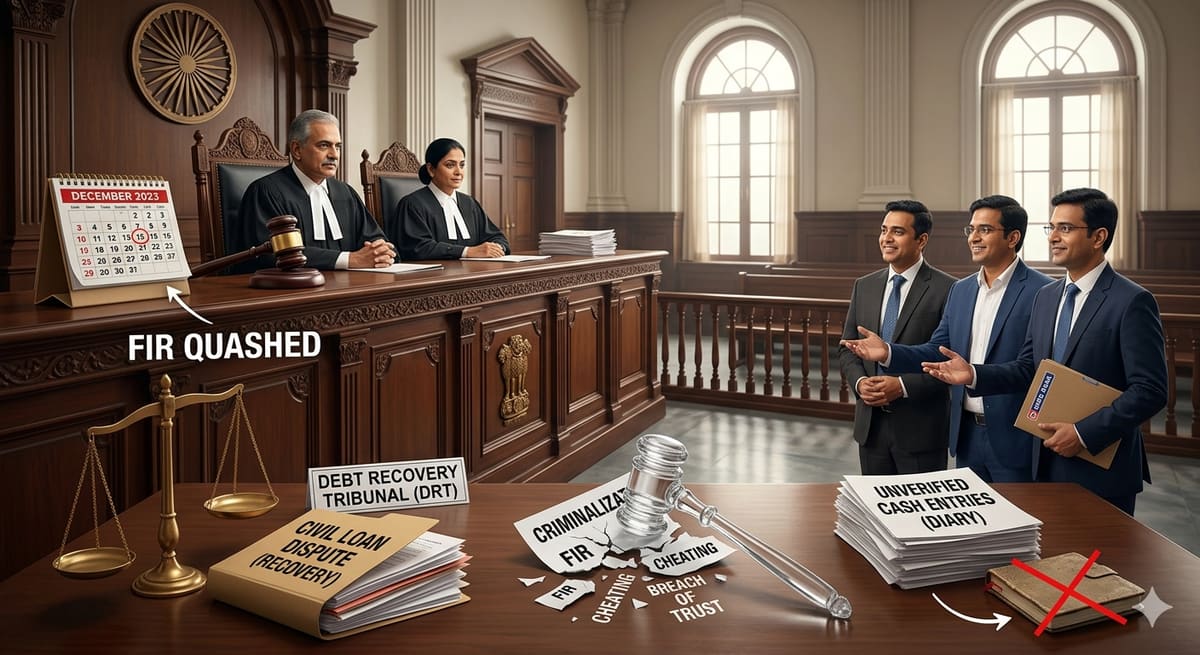
The Bombay High Court has held that initiating criminal proceedings for alleged cheating and breach of trust after a loan has been fully repaid and acknowledged by the creditor constitutes an abuse of the judicial process. The judgment underscores that civil financial disputes, even those involving secured transactions, cannot be criminalized absent clear evidence of dishonest intent from the outset.
Background & Facts
The Dispute
The present criminal application challenges the continuation of proceedings arising from First Information Report (FIR) No. 69 of 2006, registered at Vile Parle Police Station on 22 February 2006. The FIR named the two petitioners - Sayali Deepak Upasani and Rahul Vasudev Bhatt - as accused under Sections 406, 409, 420, 465, and 467 of the Indian Penal Code, 1860. The complainant, Gujarat Industrial Credit (GIC), alleged that the petitioners had fraudulently obtained a loan of Rs. 5,00,000 by misrepresenting that petitioner No. 2 was in the process of purchasing a flat from petitioner No. 1. To secure repayment, petitioner No. 2 issued two cheques of Rs. 2,50,000 each. GIC claimed that the cheques were dishonored and that the petitioners had no intention of repaying the loan.
Key Facts
- On 22 February 2006, FIR No. 69 of 2006 was registered against the petitioners.
- GIC advanced Rs. 5,00,000 as a loan to petitioner No. 1 on the representation that petitioner No. 2 was purchasing a flat.
- Two cheques of Rs. 2,50,000 each were issued by petitioner No. 2 as security for repayment.
- GIC initiated proceedings under Section 13(2) of the Securitisation and Reconstruction of Financial Assets and Enforcement of Security Interest Act, 2002, for recovery of the loan.
- On 10 April 2012, GIC issued a No Due Certificate acknowledging full repayment of the Rs. 5,00,000 loan by the petitioners.
- The Debt Recovery Appellate Tribunal, in Appeal No. 102 of 2006, noted the repayment and dismissed GIC’s recovery claim.
- The flat mortgaged to GIC was found in possession of petitioner No. 2’s family members, which triggered suspicion and led to the FIR.
Procedural History
- 22.02.2006: FIR No. 69 of 2006 registered at Vile Parle Police Station.
- 29.07.2013: Interim protection granted to petitioners by the High Court.
- 12.07.2016: High Court issued Rule Nisi in Criminal Application No. 604 of 2013, staying criminal proceedings.
- 10.04.2012: GIC issued No Due Certificate confirming repayment of Rs. 5,00,000.
- 2016 - 2023: Parallel proceedings under the Securitisation Act continued, with appellate tribunal affirming repayment.
- 18.03.2026: Judgment delivered by the Bombay High Court.
Relief Sought
The petitioners sought quashing of FIR No. 69 of 2006 and termination of all criminal proceedings, arguing that the dispute was purely civil and that the criminal machinery had been misused.
The Legal Issue
The central question was whether the initiation and continuation of criminal proceedings under Sections 406, 420, and 467 of the IPC are justified when the underlying financial liability has been fully discharged and acknowledged by the complainant through a No Due Certificate, and no material demonstrates dishonest intent at the inception of the transaction.
Arguments Presented
For the Petitioner
The petitioners’ counsel argued that the issuance of a No Due Certificate by GIC on 10 April 2012 conclusively established repayment of the loan. The certificate, being a formal admission by the creditor, negated the very foundation of the allegations of cheating and criminal breach of trust. Reliance was placed on Arnesh Kumar v. State of Bihar and Rameshwar Prasad v. State of Bihar to argue that criminal proceedings cannot be maintained where the dispute is essentially civil and the creditor has admitted satisfaction of the debt. The petitioners contended that the possession of the flat by family members, without more, cannot constitute forgery or criminal misappropriation.
For the Respondent
The State, represented by the Additional Public Prosecutor, argued that the initial misrepresentation regarding the purchase of the flat and the subsequent non-payment of the loan established a prima facie case of cheating. It was submitted that the No Due Certificate was issued under duress or as part of a settlement and could not override the criminal allegations. The State also contended that the possession of the mortgaged property by the petitioners’ family members indicated an intent to defraud the secured creditor.
The Court's Analysis
The Court examined the nature of the transaction and the subsequent developments. It emphasized that the Securitisation Act provides a comprehensive statutory framework for recovery of secured debts, and its invocation by GIC demonstrated the parties’ recognition of the civil nature of the dispute. The Court noted that the issuance of a No Due Certificate by a financial institution is not a casual or informal document - it is a formal acknowledgment of discharge of liability.
"When the creditor institution itself certifies that the loan amount has been repaid and that no further dues remain outstanding, the very basis of the allegation regarding dishonest non-repayment becomes doubtful."
The Court further observed that the Debt Recovery Appellate Tribunal had already taken note of the repayment and dismissed GIC’s recovery claim. The Court held that the mere fact that the mortgaged property remained in possession of the petitioners’ family members did not, by itself, establish criminal intent. Absent evidence that the petitioners had no intention to repay at the time of obtaining the loan, the allegations could not sustain charges under Sections 420 or 406.
The Court reiterated the principle from State of Haryana v. Bhajan Lal that courts must intervene to quash criminal proceedings where the allegations, even if true, do not disclose a cognizable offence. Here, the entire grievance arose from a settled financial transaction. Permitting the prosecution to continue would amount to misuse of criminal law to enforce a civil debt.
The Verdict
The petition succeeded. The Court made the rule absolute and quashed FIR No. 69 of 2006 in its entirety. All criminal proceedings arising from the FIR were ordered to be terminated. The Court held that the continuation of prosecution was an abuse of process and directed that no further action be taken against the petitioners in connection with the matter. There was no order as to costs.
What This Means For Similar Cases
Settlement of Civil Debt Bars Criminal Prosecution
- Practitioners must argue that a No Due Certificate or formal acknowledgment of repayment by a creditor negates the essential ingredient of dishonest intent required for offences under Sections 420 and 406 IPC.
- Where a financial dispute has been resolved through civil or statutory mechanisms (e.g., SARFAESI Act), initiating criminal proceedings is legally untenable.
Possession of Secured Property ≠ Criminal Misappropriation
- Merely retaining possession of mortgaged property after repayment does not constitute criminal breach of trust or cheating.
- Courts must distinguish between civil remedies for repossession and criminal allegations of fraud - absent proof of fraudulent intent at the time of transaction, criminal charges are improper.
Judicial Scrutiny of FIRs Is Mandatory
- Courts must conduct a preliminary review of FIRs in financial disputes to prevent misuse of criminal law.
- The Bhajan Lal test applies with heightened force where creditor institutions have admitted repayment - criminal proceedings must be quashed at the earliest stage.