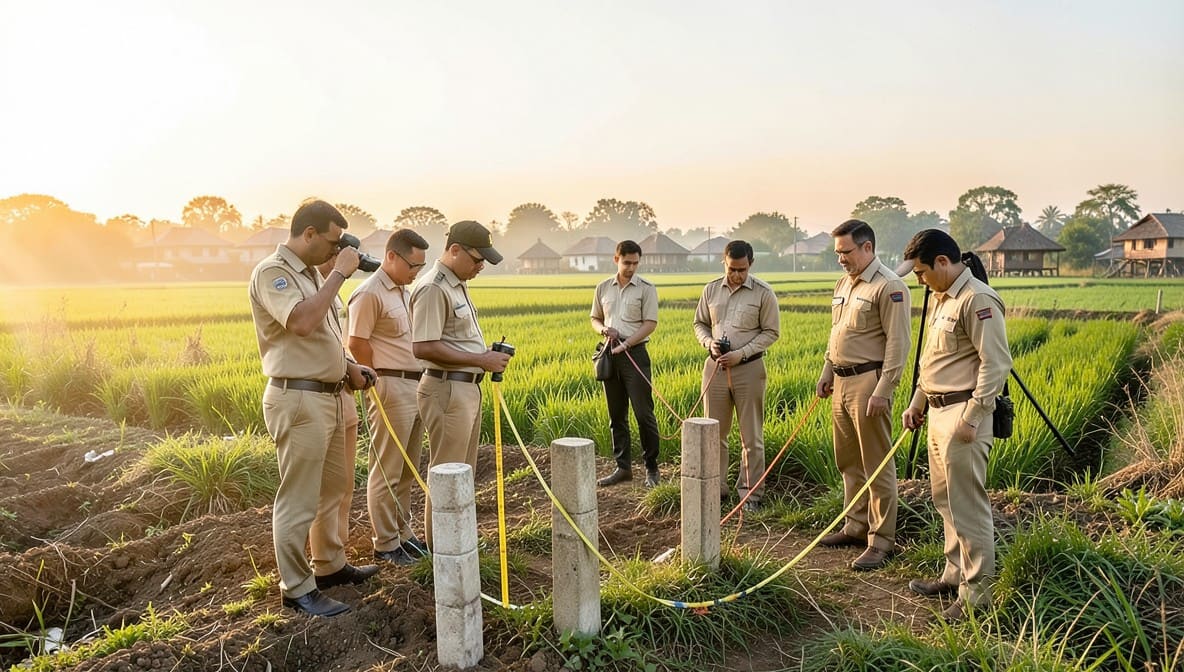
The Madhya Pradesh High Court has clarified that the authority to correct revenue records and map entries lies exclusively with the Sub-Divisional Officer under Section 115 of the M.P. Land Revenue Code, 1959. Any attempt by a Tehsildar to adjudicate such matters constitutes a jurisdictional error, rendering the proceedings void. This judgment reinforces procedural compliance in land revenue administration and underscores the necessity of due process in boundary disputes.
Background & Facts
The Dispute
The dispute arose from a claim by respondent No.1, Mahendra Singh, for the demarcation and apportionment of land bearing Survey Nos. 883/3/1 (0.084 hectare), 883/10/3 (0.073 hectare), 883/13/1 (0.422 hectare), and 871/5/2/1 (0.016 hectare) in Village Behta, Tehsil Morar, District Gwalior. He filed an application under Section 70 of the M.P. Land Revenue Code, 1959, on 08.01.2024, seeking a separate survey number for his alleged share. The petitioner, Rajendra Prakash, contested the proposed apportionment, alleging that the proceedings were conducted without notice and in violation of natural justice.
Key Facts
- The land in question is adjacent to the Gwalior-Jhansi National Highway (Gwalior Bypass), part of which was acquired by the State in 2007 under an award dated 16.11.2007
- Respondent No.1 received compensation for the acquired portion and continues to hold the remaining land
- The petitioner and respondent No.2, Jai Prakash Sharma, are brothers and sons of Patiram Sharma
- On 12.10.2018, the petitioner and respondent No.2 obtained a batankan order from the Upper Tehsildar, Circle Badagaon, in Case No. 0008/31-3/17-18, which incorrectly assigned portions of respondent No.1’s land to them
- Respondent No.1 challenged the 12.10.2018 batankan order before the Sub-Divisional Officer (Revenue), Morar, who allowed the appeal and set aside the order after the petitioner and respondent No.2 conceded the error
- After the 2018 order was set aside, respondent No.1 applied for fresh demarcation and boundary correction
- A notice dated 17.04.2024 was issued by the Patwari for spot inspection on 20.04.2024, but was never served on the petitioner
- The spot inspection was conducted on 20.04.2024 in the petitioner’s absence, resulting in an ex parte report allocating the most valuable portion of land (abutting the highway) to respondent No.1
- The Patwari’s report falsely claimed that a person named "Jagdish" had been present and consented, despite Jagdish having died prior to the inspection date
- The petitioner filed objections on 22.04.2024, challenging the legality of the inspection and the report
- The Additional Tehsildar dismissed the objections on 10.06.2024, falsely recording that notice had been served
- The Additional Collector dismissed the revision on 06.08.2024 without addressing the petitioner’s specific grounds, including the death of Jagdish and non-service of notice
Procedural History
- 03.01.2024: Proclamation issued under Section 70
- 08.01.2024: Application filed by respondent No.1 under Section 70
- 24.01.2024: First hearing; no service of notice, no Patwari report
- 07.02.2024: Adjourned; no proceedings recorded
- 13.02.2024: Adjourned again; Patwari report awaited; no notice served
- 22.02.2024: Listed but no proceedings held
- 01.04.2024: Court noted non-service of notice and non-receipt of Patwari report; adjourned to 19.04.2024
- 17.04.2024: Patwari issued notice for inspection on 20.04.2024; not served on petitioner
- 20.04.2024: Spot inspection conducted ex parte; petitioner absent
- 22.04.2024: Petitioner filed objections before Tehsildar
- 10.06.2024: Additional Tehsildar dismissed objections, falsely recording service of notice
- 06.08.2024: Additional Collector dismissed revision without addressing merits
- 24.03.2026: Writ petition decided by High Court
The Parties' Positions
Petitioner (Rajendra Prakash): Contended that the Tehsildar lacked jurisdiction, no notice was served, the spot inspection was ex parte, the Patwari report was fabricated, and the revisional authority failed to apply its mind. He sought quashing of the impugned orders.
Respondent No.1 (Mahendra Singh): Argued that the petitioner and respondent No.2 had previously conceded the error in the 2018 batankan order, that notice was duly served, and that the Tehsildar acted within jurisdiction. He claimed the petitioner was attempting to delay legitimate demarcation.
Relief Sought
The petitioner sought quashing of the orders dated 10.06.2024 and 06.08.2024, and direction for the matter to be redetermined by the competent authority under Section 115 of the M.P. Land Revenue Code, 1959, with due opportunity of hearing.
The Legal Issue
The central question was whether the Tehsildar possessed jurisdiction under Section 70 of the M.P. Land Revenue Code, 1959, to adjudicate matters concerning correction of revenue maps and boundary demarcation, or whether such authority exclusively vests in the Sub-Divisional Officer under Section 115.
Arguments Presented
For the Petitioner
The petitioner’s counsel argued that Section 70 pertains to sub-division or amalgamation of survey numbers due to change in land rights, whereas the present dispute involved correction of map entries and boundary demarcation based on possession - matters exclusively governed by Section 115. He cited the absence of service of notice on the petitioner at every stage, the ex parte nature of the spot inspection, and the fabricated claim of Jagdish’s presence as clear violations of natural justice. He further contended that the revisional authority’s mechanical affirmation of the Tehsildar’s order without reasoning rendered it legally unsustainable.
For the Respondent
The respondent’s counsel argued that the proceedings were conducted after proper notice and that the petitioner and respondent No.2 had previously conceded the error in the 2018 batankan order. He submitted that the Tehsildar’s role was limited to facilitating the Patwari’s report and that the correction sought was incidental to the application under Section 70. He further claimed that the petitioner’s challenge was a tactic to obstruct lawful demarcation after having previously admitted the incorrectness of their own claim.
The Court's Analysis
The Court undertook a detailed examination of the nature of the relief sought and the statutory framework under the M.P. Land Revenue Code, 1959. It observed that the application filed by respondent No.1 sought not a sub-division of survey numbers, but correction of revenue maps and demarcation of boundaries based on possession - a function explicitly assigned to the Sub-Divisional Officer under Section 115.
"The relief sought in substance reflected from the application is basically correction of revenue records and maps on the basis of apportionment of holding already existed on the basis of possession and did not pertain to re-numbering, sub-division or amalgamation of survey numbers, block numbers or plot numbers due to change in land rights."
The Court emphasized that Section 115 mandates a written report from the Tehsildar and an opportunity of hearing to all parties - conditions that were not met in the impugned proceedings. The Tehsildar’s purported exercise of jurisdiction under Section 70 was therefore a clear case of jurisdictional infirmity.
The Court further noted that the revisional authority failed to address the jurisdictional defect, instead offering a cryptic affirmation without reasoning. The Court held that such mechanical approval of an illegal order cannot be sustained.
"The order appears to be cryptic and does not reflect due application of mind to the material available on record."
The Court also rejected the respondent’s claim of notice being served, citing the complete absence of any order-sheet recording service of notice between 24.01.2024 and 20.04.2024. The Patwari’s report, which falsely claimed the presence of a deceased person, was declared unreliable.
The Verdict
The petition was allowed. The impugned orders dated 10.06.2024 and 06.08.2024 were set aside. The matter was remanded to the Sub-Divisional Officer (Revenue), who shall now adjudicate the dispute under Section 115 of the M.P. Land Revenue Code, 1959. The Sub-Divisional Officer is directed to conduct a fresh hearing, consider all objections, and pass a reasoned order uninfluenced by the impugned proceedings. Both parties are directed to appear before the Sub-Divisional Officer on 20.04.2026.
What This Means For Similar Cases
Jurisdictional Limits Under Section 115 Are Absolute
- Practitioners must verify whether a dispute involves boundary demarcation or map correction - if so, jurisdiction lies only with the Sub-Divisional Officer under Section 115, not the Tehsildar under Section 70
- Any order passed by a Tehsildar in such matters is void ab initio and subject to immediate quashing on jurisdictional grounds
- Applications filed under Section 70 for boundary correction must be reclassified or transferred to the competent authority
Natural Justice Cannot Be Overridden by Administrative Convenience
- Non-service of notice, even if claimed, must be substantiated by order-sheets or service records
- Ex parte inspections without notice are fatal to the validity of revenue proceedings
- Fabricated or false attestations in Patwari reports render the entire report inadmissible
- Revisional authorities must record reasons; mechanical affirmations are legally unsustainable
Prior Concessions Do Not Cure Procedural Illegality
- Even if parties previously admitted an error in earlier proceedings, subsequent proceedings must still comply with statutory procedure
- A party’s prior conduct cannot waive the requirement of due process in revenue matters
- Courts will not permit procedural shortcuts, even where parties appear to be acting in bad faith