The Customs, Excise and Service Tax Appellate Tribunal ruled that UltraTech Cement Ltd's investment in railway wagons under the Liberalised Wagon Investment Scheme (LWIS) and the consequent freight concession do not constitute a taxable service, thereby quashing the service tax, interest and penalty demands.
Background & Facts
The Dispute
M/s UltraTech Cement Ltd (appellant), a cement and clinker manufacturer, procured private railway wagons under the LWIS to transport its own finished products. The Ministry of Railways, through the scheme, granted the appellant a freight concession as an incentive for the capital investment. The Department of Central Tax issued demands for service tax, interest and penalties under sections 76, 77 and 78 of the Finance Act, 1994, alleging that the concession represented consideration for a supply of tangible goods for use.
Key Facts
- UltraTech Cement Ltd is located at Bhogasamudram Village, Tadipatri Mandal, Andhra Pradesh.
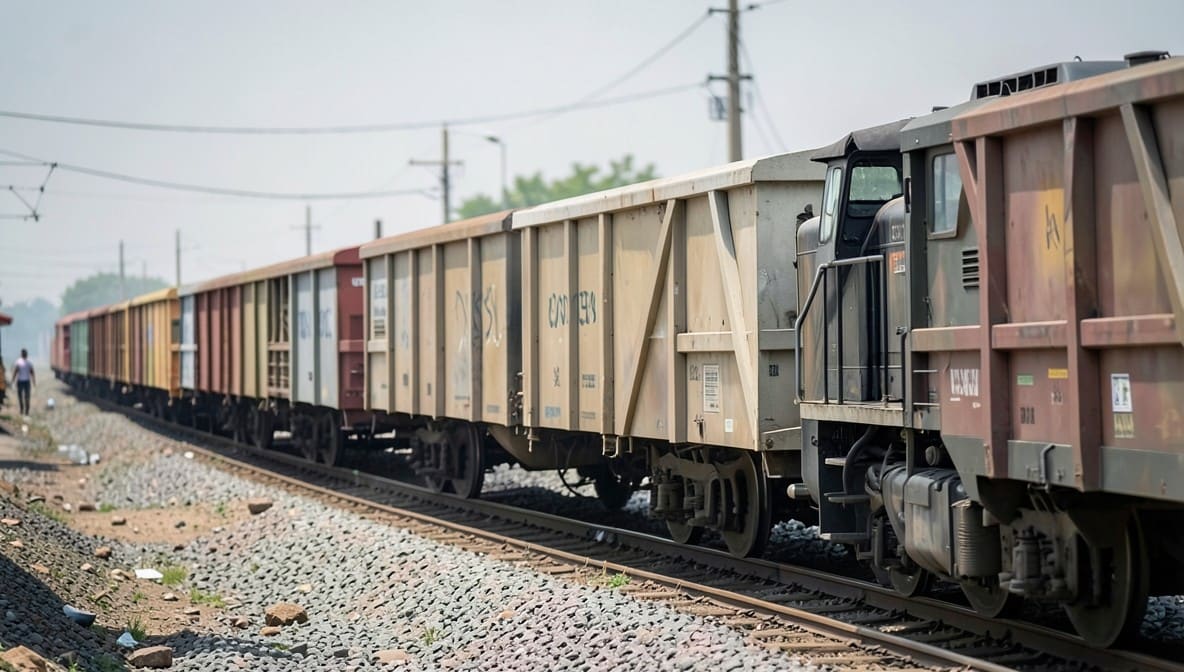
- The appellant purchased BCCW railway wagons at its own cost solely for moving its own cement cargo.
- Under LWIS, the Railways attached the appellant's wagons to its locomotives and transported the goods on payment of freight, reduced by the concession.
- The concession was framed as a policy incentive, not as payment for any service rendered by the appellant.
- The Department treated the concession as consideration for a taxable service of "supply of tangible goods for use".
Procedural History
- 15.05.2013: Order-in-Appeal No.18/2013 (T) issued by Commissioner of Customs, Central Excise & Service Tax (Appeals), Guntur.
- 27.04.2016: Order-in-Appeal No.TTD-EXCUS-000-APP-003-16-17 dated 27.04.2016.
- 26.12.2017: Orders-in-Appeal No.TTD-EXCUS-000-APP-081-17-18 and No.TTD-EXCUS-000-APP-082-17-18 dated 26.12.2017.
- 18.09.2019: Order-in-Appeal No.TTD-EXCUS-000-APP-029-19-20 dated 18.09.2019.
- Appeals filed as Service Tax Appeal Nos. 27580/2013, 30830/2016, 30312-30314/2018 and 30108/2020.
- 06.07.2026: Hearing before the Tribunal (Division Bench - Court No. I).
- 28.07.2026: Final order delivered, setting aside the service tax demands.
Parties' Positions
- Appellant: Contended that no contractual obligation existed to provide any service to the Railways; the concession was merely an incentive and not consideration; there was no service provider-service recipient relationship.
- Respondent: Asserted that by allowing the Railways to attach its wagons, the appellant supplied tangible goods for use and that the freight concession constituted consideration for such a service.
Relief Sought
The appellant sought the setting aside of the service tax, interest and penalty demands and any consequential relief, if any, in accordance with law.