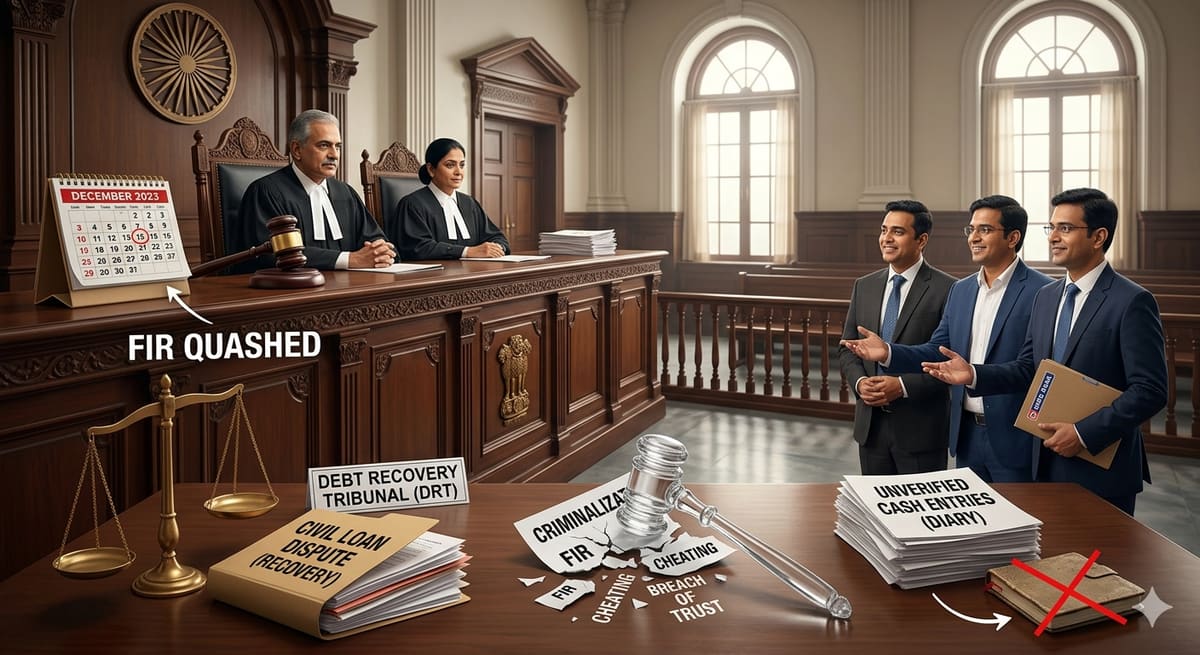
The Bombay High Court has reaffirmed that repayment of a loan obtained through fraudulent means does not automatically extinguish criminal liability, particularly when public depositors' money is involved and statutory offences like forgery and cheating are alleged. This judgment clarifies the limits of inherent powers under Section 482 CrPC in cases of economic crimes with societal ramifications.
Background & Facts
The Dispute
The applicant, Anil S/o Lekhraj Gambhir, is accused in FIR No. 338/2007 for allegedly obtaining a cash credit loan of Rs. 10 lakhs from Samta Sahakari Bank Limited by submitting forged documents and mortgaging property not owned by him. The property, Plot Nos. 7, 8 and 9 in Jaripatka, was registered in the name of Vinodkumar Jain, a co-owner of a Hindu Undivided Family property. The applicant allegedly obtained a power of attorney from Jain to mortgage the property, despite knowing it was jointly owned and already pledged to another lender, M/s Vinsha Investment and Leasing. The audit report revealed a larger conspiracy involving bank officials and 12 group loans, defrauding depositors of Rs. 145.60 crore.
Procedural History
- 1993: Bank issued a letter acknowledging repayment of loan by applicant
- 2007: FIR registered under Sections 406, 408, 409, 467, 468, 471, 420, 201, 120B, 109 IPC, Section 65 IT Act, and Sections 3 and 4 of MPID Act
- 2009: Bank issued Clearance Certificate confirming repayment under one-time settlement
- 2019: Special Case No. 14/2019 filed based on audit findings
- 2025: Applicant filed Criminal Application under Section 482 CrPC seeking quashing of FIR
Relief Sought
The applicant sought quashing of the FIR and all consequential proceedings on the ground that the loan had been fully repaid, the dispute was settled, and no criminal intent existed at the time of loan disbursement.
The Legal Issue
The central question was whether repayment of a loan obtained through alleged forgery, false representation, and mortgaging of third-party property can justify quashing of criminal proceedings under Section 482 CrPC, particularly when the fraud involves public depositors' money and offences under Sections 467, 468, and 471 IPC.
Arguments Presented
For the Appellant/Petitioner
The applicant relied on Gian Singh v. State of Punjab and CBI v. Narendra Lal Jain to argue that since the loan was fully repaid and a Clearance Certificate was issued, the dispute had a predominantly civil character. He contended that Section 420 IPC requires dishonest intent at inception, which was absent, and that continuation of proceedings would amount to abuse of process. He emphasized that the bank had no outstanding claim and that quashing was warranted under the settled principle that civil disputes should not be converted into criminal proceedings.
For the Respondent/State
The State countered that the repayment was part of a one-time settlement scheme and did not negate the criminal acts committed during loan acquisition. It highlighted that the property mortgaged was not owned by the applicant, was already pledged to another entity, and belonged to a Hindu Undivided Family without consent of coparceners. The State argued that the offences under Sections 467, 468, and 471 IPC involve forgery of documents and use of forged documents, which are non-compoundable and affect public confidence in financial institutions. It relied on CBI v. Jagjit Singh to assert that bank frauds are social wrongs with wide societal impact, beyond private disputes.
The Court's Analysis
The Court examined the nature of the offences and the scope of Section 482 CrPC in light of precedents. It distinguished between private civil disputes and economic crimes involving public funds. The Court noted that while Gian Singh permits quashing in cases with a predominant civil flavour, such relief is unavailable where offences involve forgery of documents, misrepresentation to financial institutions, and fraud against depositors.
"The offences when committed in relation with banking activities including offences under Sections 420/471 IPC have harmful effect on the public and threaten the well-being of the society."
The Court emphasized that Sections 467, 468, and 471 IPC are not merely civil wrongs but serious offences against public order and financial integrity. The fact that the property mortgaged was jointly owned and already pledged demonstrated a deliberate scheme to deceive the bank. The Court rejected the argument that repayment negates criminal liability, stating: "Repayment under a settlement scheme does not erase the prior criminal conduct that endangered public deposits."
It further held that the involvement of bank officials in a systemic fraud of over Rs. 145 crore elevated the matter beyond a private dispute. The Court cited CBI v. Jagjit Singh to reinforce that bank frauds are "social wrongs" with "immense societal impact," and that quashing proceedings would undermine deterrence and public trust in the banking system.
The Verdict
The applicant’s petition was dismissed. The Court held that repayment of a loan does not absolve an accused of criminal liability for forgery, false representation, and mortgaging third-party property in a bank fraud case. The FIR and proceedings under Sections 467, 468, 471 IPC and the MPID Act shall continue, as the case involves public interest and statutory offences that cannot be quashed merely on the basis of settlement.
What This Means For Similar Cases
Settlement Does Not Erase Criminal Conduct
- Practitioners must argue that repayment or settlement under one-time schemes does not negate the existence of dishonest intent at the time of transaction
- In cases involving forged documents or false collateral, courts will examine the nature of the fraud, not just the outcome
- Even if the bank is made whole, the state retains locus to prosecute offences against public financial systems
Forgery Offences Are Non-Quashable Even With Repayment
- Sections 467, 468, and 471 IPC are non-compoundable and inherently public in nature
- Courts will not quash proceedings under these sections merely because the victim bank received payment
- The presence of multiple forged documents or repeated mortgaging of the same asset strengthens the case for prosecution
Bank Fraud Is a Social Wrong, Not a Private Dispute
- Cases involving depositors’ money are treated as crimes against society, not just the bank
- The CBI v. Jagjit Singh doctrine now firmly applies to cooperative banks under MPID Act
- Legal teams must prepare for heightened scrutiny when seeking quashing in financial fraud cases - focus on systemic fraud, not individual repayment