Topic

Section 144C

Section 144C of the Income Tax Act, 1961, governs the procedure for assessment in cases where the Dispute Resolution Panel (DRP) issues directions, mandating draft assessment orders and compliance with DRP rulings before final orders are passed.

6 articlesLatest July 2026
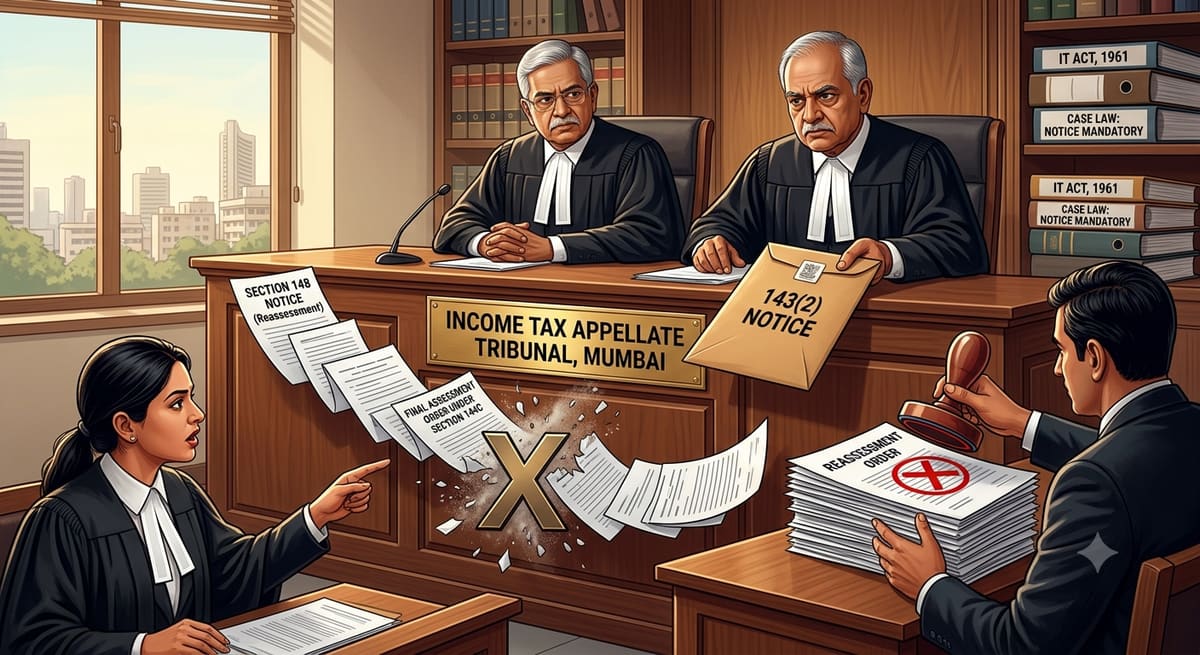
Section 143(2) Notice Mandatory for Reassessment | Non-Compliance Vitiates Assessment Under Section 144C : ITAT Mumbai
Case Law Analysis
|Income Tax Appellate Tribunal

Section 143(2) Notice Mandatory for Reassessment | Non-Compliance Vitiates Assessment Under Section 144C : ITAT Mumbai

ITAT Mumbai rules that failure to issue a mandatory notice under Section 143(2) during reassessment proceedings renders the entire assessment void ab initio. The tribunal held that issuing a demand notice alongside a draft assessment order under Section 144C without adhering to procedural safeguards constitutes a jurisdictional error, impacting all taxpayers undergoing reassessment.
Section 144C(13) IT Act | Limitation Period for Assessment Order Starts from DRP Direction Upload Date on ITBA Portal : ITAT Bangalore
Case Law Analysis
|Income Tax Appellate Tribunal

Section 144C(13) IT Act | Limitation Period for Assessment Order Starts from DRP Direction Upload Date on ITBA Portal : ITAT Bangalore

ITAT Bangalore rules that the one-month limitation under Section 144C(13) of the Income Tax Act begins from the date DRP directions are uploaded to the ITBA portal, not from the Assessing Officer's actual receipt. The tribunal quashed the assessment order for being time-barred, reinforcing procedural compliance in faceless assessments.

Section 144(C) Income Tax Act | Draft Assessment Order Mandatory for Eligible Assessees; Non-Compliance Renders Final Order Void : Uttarakhand HC
Case Law Analysis
|Uttarakhand High Court

Section 144(C) Income Tax Act | Draft Assessment Order Mandatory for Eligible Assessees; Non-Compliance Renders Final Order Void : Uttarakhand HC

Uttarakhand High Court quashes a final tax assessment order for failure to issue a mandatory draft assessment under Section 144(C) of the Income Tax Act. The ruling reinforces that eligible assessees must be given an opportunity to respond before a final order is passed, ensuring procedural fairness in tax assessments.