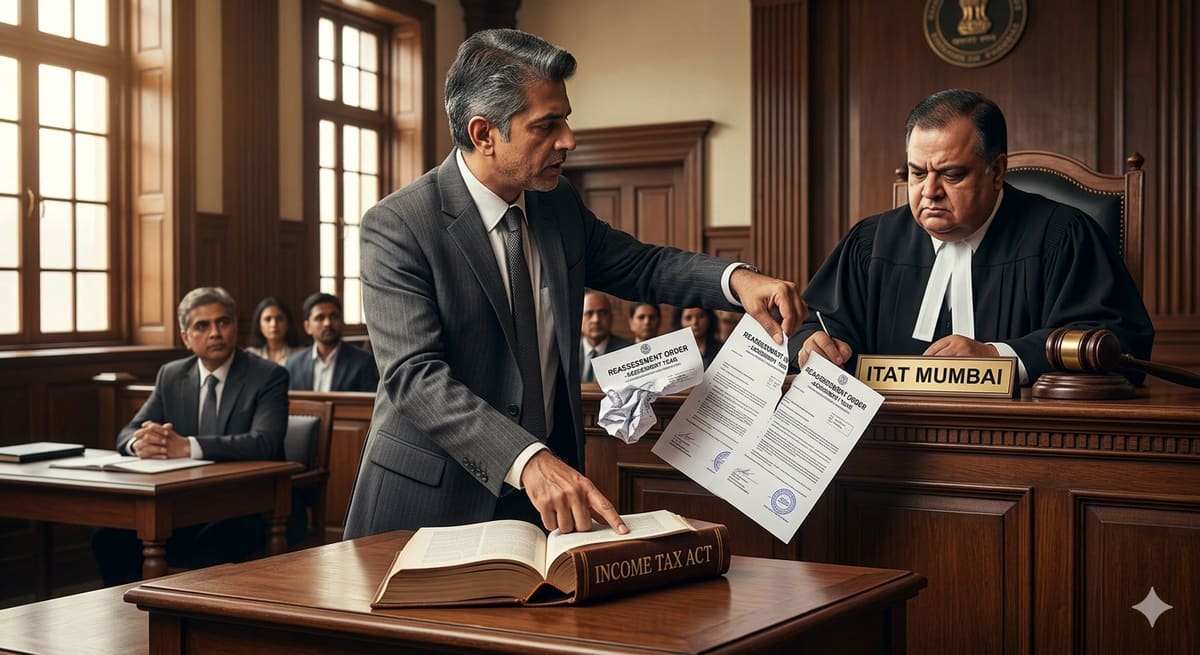
The ITAT Dehradun Bench has delivered a significant clarification on the limits of revisionary powers under Section 263 of the Income Tax Act, holding that once a higher authority has quashed a revisional order, a subordinate authority cannot reissue the same order on identical grounds. This ruling reinforces the principle of finality in administrative adjudication and prevents circular litigation.
Background & Facts
The Dispute
The appellant, Prashant Malik, challenged the order passed by the Commissioner of Income Tax (Appeals) under Section 263 of the Income Tax Act, 1961, which had set aside the original assessment order and directed the Assessing Officer to reassess the taxpayer’s income for Assessment Year 2015-16. The revision was initiated by the Principal Chief Commissioner of Income Tax on grounds of alleged error prejudicial to revenue.
Procedural History
- 2021: Assessing Officer passed original assessment order under Section 144.
- 2021: Principal Chief Commissioner invoked Section 263 to revise the assessment, citing error prejudicial to revenue.
- 2024: A co-ordinate Bench of the ITAT Dehradun, in ITA No. 35/DDN/2022, quashed the PCIT’s Section 263 order, holding it was not justified.
- 2025: Despite the earlier quashing, the CIT(A) reissued the same revisional order under Section 263, relying on identical grounds.
- 2026: The appellant filed the present appeal against the CIT(A)’s order.
Relief Sought
The appellant sought quashing of the CIT(A)’s order, arguing that it violated the principle of res judicata and judicial consistency, and amounted to an abuse of process.
The Legal Issue
The central question was whether the Commissioner of Income Tax (Appeals) could lawfully reissue a revisional order under Section 263 of the Income Tax Act after a co-ordinate Bench of the ITAT had already quashed the original revisional order on identical grounds.
Arguments Presented
For the Petitioner
The appellant’s representatives argued that the CIT(A)’s order was a direct contravention of the principle of res judicata by substance, even if not by form. They relied on State of U.P. v. Mohammad Noor and Bhagwati Prasad v. CIT to contend that once a judicial authority has finally decided an issue, subordinate authorities cannot re-agitate it. They emphasized that the co-ordinate Bench’s quashing order was binding in effect, and the CIT(A)’s reissuance was an attempt to circumvent judicial authority.
For the Respondent
The Revenue contended that the CIT(A) was not bound by the co-ordinate Bench’s order, as it was not a superior court and the earlier order did not formally bind the CIT(A) under Section 263. They argued that the CIT(A) had independent jurisdiction to examine whether the original assessment was erroneous and prejudicial to revenue, irrespective of the ITAT’s prior decision.
The Court's Analysis
The Bench examined the nature of Section 263 revisional power, noting that it is not an appellate remedy but a supervisory power meant to correct manifest errors prejudicial to revenue. However, the Court held that such power cannot be exercised in a manner that undermines judicial finality. The Bench observed that the co-ordinate Bench’s order, though not technically binding under stare decisis, carried persuasive authority and established a clear legal position on the facts.
"The revisional order under Section 263 cannot be resurrected after it has been judicially quashed on merits by a co-ordinate Bench. To permit such a course would render judicial pronouncements meaningless and invite arbitrariness in tax administration."
The Court further noted that the CIT(A) did not identify any new material, error, or change in circumstances to justify re-initiating the revision. The order was therefore found to be a mechanical reiteration of a已被撤销的决定, violating the doctrine of consistency and the spirit of natural justice.
The Verdict
The appellant won. The ITAT Dehradun quashed the CIT(A)’s order under Section 263, holding that revisional power cannot be re-exercised after a co-ordinate Bench has already quashed the same order on identical grounds. The appeal was allowed, and the original assessment stood restored.
What This Means For Similar Cases
Revisional Orders Cannot Be Rebooted
- Practitioners must challenge any re-initiation of a quashed Section 263 order as an abuse of process.
- Revenue authorities cannot use procedural technicalities to revive orders judicially set aside.
- A co-ordinate Bench’s quashing order, while not binding, creates a strong precedent that must be respected in administrative practice.
Judicial Finality Trumps Administrative Discretion
- Tax authorities must accept judicial determinations on factual and legal merits, even if rendered by co-ordinate benches.
- Repeated invocation of Section 263 on the same facts without new evidence invites judicial censure.
- This ruling strengthens the taxpayer’s right to finality and discourages harassment through repetitive revisional proceedings.
Procedural Compliance Is Non-Negotiable
- Any revision under Section 263 must be based on fresh, material grounds - not recycled arguments.
- Assessing Officers and CIT(A)s must document why prior judicial findings are inapplicable before initiating revision.
- Failure to do so renders the order vulnerable to immediate quashing on grounds of mala fide or procedural arbitrariness.