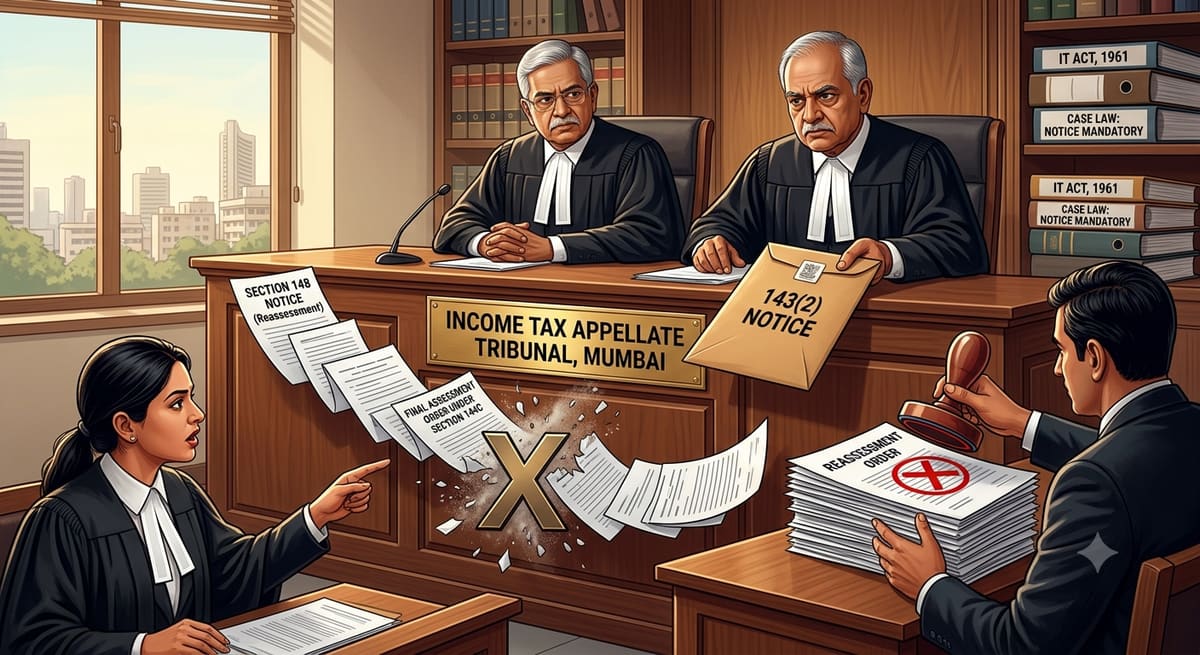
The Income Tax Appellate Tribunal, Delhi, has unequivocally held that the issuance of a mandatory notice under Section 143(2) of the Income Tax Act is non-negotiable in all cases where a return is filed in response to a notice under Section 148, irrespective of whether the return is deemed invalid due to lack of e-verification or delayed submission. This ruling reinforces procedural compliance as a jurisdictional requirement, not a mere formality.
Background & Facts
The Dispute
The assessee, Kritika Jain, filed a return of income on 30.04.2022 in response to a notice issued under Section 148 of the Income Tax Act for Assessment Year 2018-19. The Assessing Officer (AO) treated this return as "invalid" because it was not e-verified, despite the assessee having submitted a physically signed ITR-V to the CPC, Bangalore, in accordance with the Income Tax Department’s own guidelines. The AO proceeded to complete the assessment under Section 144B read with Section 147 without issuing any notice under Section 143(2).
Procedural History
- 30.04.2022: Assessee filed return in response to Section 148 notice
- 16.06.2023: AO issued notice under Section 142(1) declaring the return invalid due to lack of e-verification
- 18.07.2023: Assessee replied with physical ITR-V and request for condonation, as per departmental guidelines
- 22.01.2025: CIT(A) upheld the AO’s order, rejecting the contention that Section 143(2) notice was mandatory
- 10.03.2026: ITAT Delhi allowed the appeal, quashing the assessment
Relief Sought
The assessee sought quashing of the assessment order on the ground that the failure to issue a notice under Section 143(2) rendered the entire proceeding void ab initio, regardless of the return’s technical status.
The Legal Issue
The central question was whether Section 143(2) mandates the issuance of a notice prior to framing an assessment when the return is filed in response to a notice under Section 148, even if the return is treated as invalid due to non-e-verification or delay.
Arguments Presented
For the Appellant/Petitioner
The appellant relied on multiple precedents including Anil Agarwal (HUF) v. ITO, PCIT v. Staunch Marketing (P) Ltd., and CIT v. Laxman Das Khandelwal to argue that: (1) once a return is filed in response to a Section 148 notice, it becomes a valid return for assessment purposes; (2) the AO’s reliance on the return’s declared income to compute additions demonstrates acceptance of the return; (3) the department’s own guidelines permit physical ITR-V submission as an alternative to e-verification; and (4) Section 143(2) notice is jurisdictional and cannot be waived even for belated or technically defective returns.
For the Respondent/State
The Revenue contended that since the return was not e-verified and ITR-V was received after the stipulated deadline, the return was invalid under Rule 12 of the Income Tax Rules, and therefore, Section 143(2) did not apply. It further argued that the AO had sufficient information to proceed under Section 144B and that the absence of notice did not prejudice the assessee.
The Court's Analysis
The Tribunal examined the statutory scheme of Section 143(2) and its interaction with Section 148. It emphasized that Section 143(2) is not contingent on the validity of the original return under Section 139, but applies whenever any return is filed - whether timely, belated, or in response to a notice under Section 148.
"Once a return is filed notice under Section 143(2) of the Act to the assessee is mandatory prior to framing an assessment. The question of framing an assessment ex parte without even issuing a notice under Section 143(2) of the Act did not arise."
The Court distinguished the Revenue’s reliance on technical defects in e-verification, noting that the department’s own guidelines explicitly recognize physical ITR-V as a valid mode of verification. The AO’s conduct - taking the return’s declared income as the starting point for computation - constituted de facto acceptance of the return. The Tribunal held that treating the return as invalid after acting upon it was arbitrary and contrary to the principle of consistency.
It further affirmed that the Supreme Court in ACIT v. Hotel Blue Moon and the Delhi High Court in PCIT v. Staunch Marketing had settled that Section 143(2) notice is mandatory and non-waivable. The failure to issue it renders the assessment void ab initio, irrespective of whether the assessee suffered prejudice.
The Verdict
The assessee won. The ITAT Delhi held that Section 143(2) notice is mandatory for all returns filed in response to Section 148 notices, regardless of e-verification status or delay. The assessment order was quashed as void ab initio for non-compliance with this jurisdictional requirement.
What This Means For Similar Cases
Notice Under Section 143(2) Is Jurisdictional
- Practitioners must now treat any failure to issue Section 143(2) notice as a fatal defect, even in reassessment cases
- AO’s reliance on return figures cannot be used to justify bypassing notice requirements
- Appeals against assessments without Section 143(2) notice should be framed as jurisdictional challenges, not procedural irregularities
E-Verification Defects Do Not Nullify Return Status
- Physical ITR-V submission is a legally recognized alternative under departmental guidelines
- AO cannot declare a return invalid solely on e-verification failure if physical copy was sent within reasonable time
- Taxpayers should retain proof of postal dispatch and acknowledgment for ITR-V submissions
Precedents Bind All Authorities
- ITAT Delhi’s reliance on Anil Agarwal, Staunch Marketing, and Laxman Das Khandelwal establishes binding precedent for all benches
- Revenue authorities must update internal manuals to reflect that Section 143(2) applies to all returns filed under Section 148
- Practitioners should cite these judgments in all pending reassessment appeals where notice is absent