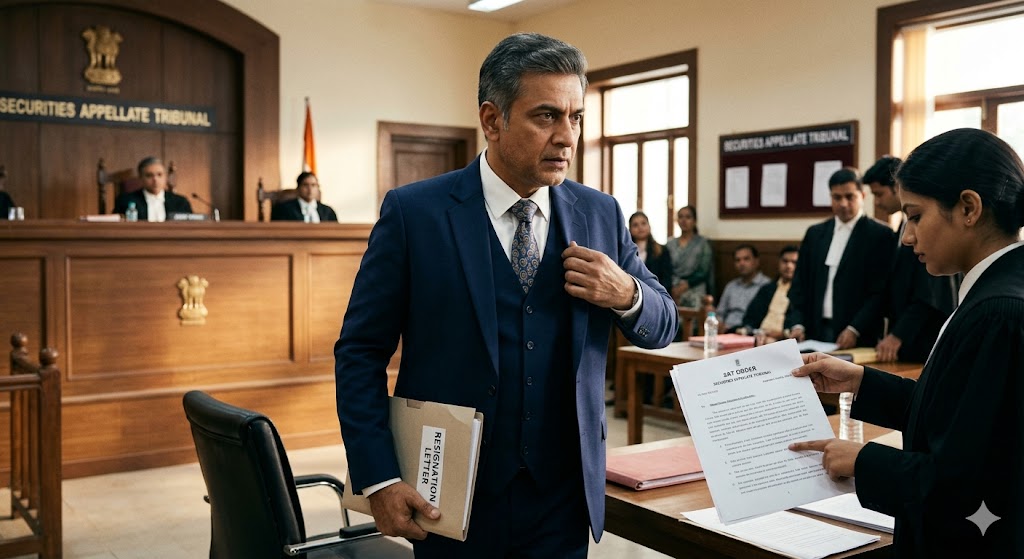
The Securities Appellate Tribunal has reaffirmed a foundational principle of investor protection: unregistered investment advisors cannot retain any fees collected through illegal advisory activities, even if no other investors come forward to claim refunds. This judgment clarifies that SEBI’s regulatory mandate extends beyond individual complaints to the systemic integrity of the securities market.
Background & Facts
The Dispute
The appellant, Maneesh Pavar, operated a proprietary investment advisory firm named Mapple Research without registration under the SEBI (Investment Advisers) Regulations, 2013. The Securities and Exchange Board of India (SEBI) received a complaint from Mr. Jitendra Suthar, who claimed to have lost ₹5,000 based on advice from Mapple Research. SEBI initiated an inquiry and issued a Show Cause Notice (SCN) to the appellant, alleging violations of Sections 11(1), 11(4), and 11B of the SEBI Act, 1992.
Key Facts
- The appellant did not respond to the SCN.
- SEBI conducted ex-parte adjudication proceedings.
- The Whole Time Member (WTM), SEBI, passed an order on 22.09.2022, quantifying the total fees collected by the appellant through unregistered advisory services at ₹68,58,045.65.
- The order directed the appellant to:
- Refund all money received from investors as fees or consideration for unregistered advisory services within three months.
- Publish public notices in two national dailies (one English, one Hindi) and one local daily with wide circulation, detailing refund modalities and contact information.
- File a compliance report certified by an independent Chartered Accountant within 15 days of completing refunds.
- On 28.01.2023, the appellant submitted a compliance report claiming:
- Refund of ₹5,000 to the original complainant.
- Publication of notices in two national dailies and one local daily.
- No other claims received from investors.
- That he was a victim of fraud by former associates who used his name to run the business.
- The appellant did not challenge the adjudication order dated 22.09.2022.
- On 19.01.2024, SEBI issued a Recovery Certificate demanding ₹80,24,914, which included the unrefunded amount of ₹68,58,045.65 plus interest and costs.
Procedural History
- 22.09.2022: WTM, SEBI, passed adjudication order under Sections 11(1), 11(4), and 11B of the SEBI Act.
- 28.01.2023: Appellant filed compliance report with SEBI.
- 19.01.2024: Recovery Certificate issued by SEBI’s Recovery Officer.
- 15.04.2024: Appeal No. 573 of 2024 filed before the Securities Appellate Tribunal.
- 21.04.2026: Appeal heard and reserved.
- 28.04.2026: Judgment pronounced.
Relief Sought
The appellant sought quashing of the Recovery Certificate dated 19.01.2024, arguing that since no other investors had claimed refunds and he had complied with the public notice requirement, no further recovery was justified.
The Legal Issue
The central question was whether an unregistered investment advisor, who has been ordered to refund all fees collected from investors under the SEBI Act, may retain the unrefunded portion merely because no other investors have come forward to claim their money.
Arguments Presented
For the Appellant
Mr. Manish Gupta argued that the appellant had fully complied with the adjudication order by refunding ₹5,000 to the complainant and publishing the required public notices. He contended that since no other investor had filed a claim in response to the notices, there was no outstanding liability. He relied on principles of natural justice and proportionality, asserting that recovery of the entire ₹68.58 lakhs without any claim from other investors was arbitrary and unjust.
For the Respondent
Mr. Manish Chhangani, for SEBI, submitted that the adjudication order was final and unchallenged. He emphasized that the SEBI Act and regulations are designed to deter unregistered advisory activities and prevent unjust enrichment. He cited Ankit Goel v. SEBI and Anoop Singh Tomar v. SEBI to establish that fees collected by unregistered advisors are illegal and cannot be retained under any circumstances, regardless of whether claims are made. The obligation to refund is absolute and not contingent on investor action.
The Court's Analysis
The Tribunal examined the statutory framework under Sections 11(1), 11(4), and 11B of the SEBI Act, which empower SEBI to take measures to protect investor interests and prevent unfair trade practices. The Tribunal noted that the appellant had not filed any appeal or review against the adjudication order dated 22.09.2022, thereby accepting its findings, including the quantification of ₹68,58,045.65 as total illegal receipts.
"We are of the opinion that the appellant, in any case, is not entitled to retain the amount collected illegally without getting itself registered under the relevant regulations."
The Tribunal reaffirmed its consistent jurisprudence in Ankit Goel, Way2Gains, and Anoop Singh Tomar, holding that the very nature of unregistered advisory activity renders the collected fees unlawful. The obligation to refund is not a remedial measure contingent on investor claims but a punitive and deterrent mechanism to strip the violator of all ill-gotten gains.
The Tribunal rejected the appellant’s argument that non-claim by other investors absolves him of liability. It held that the public notice requirement serves to notify potential victims, not to shift the burden of claiming onto them. The duty to refund rests entirely on the violator, and failure to do so constitutes continued unlawful retention of funds.
The Recovery Certificate, therefore, was not an independent enforcement action but a mechanical implementation of a final adjudication order. The Tribunal found no legal or factual basis to interfere with it.
The Verdict
The appeal was dismissed. The Securities Appellate Tribunal upheld the Recovery Certificate dated 19.01.2024, directing the appellant to pay ₹80,24,914, comprising the unrefunded amount of ₹68,58,045.65, interest, and costs. The Tribunal confirmed that unregistered investment advisors are legally obligated to refund all fees collected, irrespective of whether investors have filed claims, and may not retain any portion of such sums.
What This Means For Similar Cases
Fees Collected Illegally Must Be Fully Refunded - No Exceptions
- Practitioners representing unregistered advisors must advise clients that any fees received without SEBI registration are legally forfeitable in full.
- Compliance with public notice requirements does not discharge the obligation to refund; full repayment is mandatory.
- Failure to refund even a single rupee of collected fees may trigger recovery proceedings under SEBI’s enforcement powers.
Finality of Adjudication Orders Is Absolute
- Adjudication orders under Section 11B become binding if not appealed within the statutory period.
- Recovery Certificates issued thereafter are not subject to collateral challenge on factual grounds.
- Legal arguments based on lack of investor claims or alleged victimhood are legally irrelevant once the quantum of illegal receipts is finalized.
SEBI’s Deterrent Framework Is Non-Negotiable
- The Tribunal’s reasoning underscores that SEBI’s regulatory regime prioritizes market integrity over individualized victim compensation.
- The law does not permit unregistered advisors to profit from their illegality, even if no one else comes forward.
- Practitioners must advise clients to register before offering advisory services - retroactive compliance is not a defense.