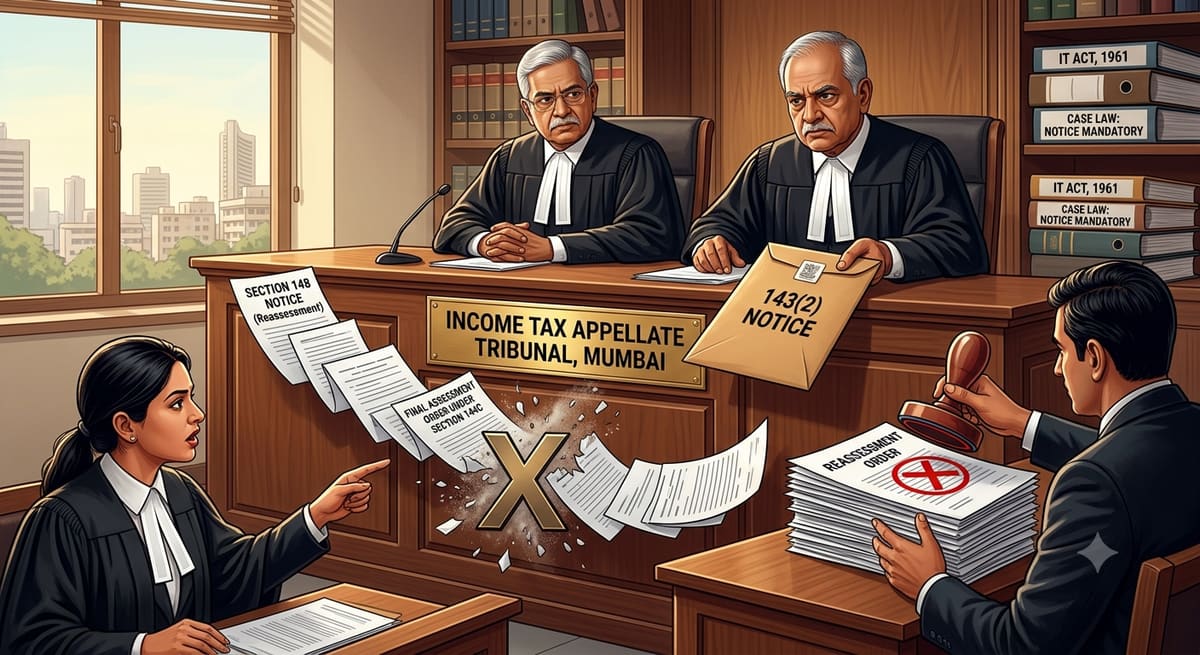
The Income Tax Appellate Tribunal, Jaipur Bench has delivered a critical ruling on procedural compliance in tax assessments for non-resident assessees. The Tribunal held that failure to issue a draft assessment order under Section 144C(1) of the Income Tax Act, 1961 for a non-resident assessee renders the entire assessment void ab initio, regardless of the merits of additions made. This judgment underscores the mandatory nature of statutory procedural safeguards in tax proceedings.
Background & Facts
The Dispute
The appellant, Karan Singh Rathore, a non-resident individual, was subjected to reassessment proceedings under Section 147 read with Section 144 of the Income Tax Act for Assessment Year 2016-17. The Assessing Officer (AO) initiated proceedings based on information from the department's AIS/ITS software, alleging cash deposits of Rs. 13,17,000 and purchase of immovable property worth Rs. 65,00,000. The AO completed the assessment without issuing a draft assessment order, a procedural requirement for non-resident assessees under Section 144C of the Act.
Key Facts
- The assessee was a non-resident during the relevant assessment year (AY 2016-17), as evidenced by passport records showing his stay in India did not exceed 182 days in the financial year 2015-16 or 365 days in the preceding four years
- The AO issued a notice under Section 142(1) on 15.12.2023, requiring the assessee to furnish details of income, bank accounts, and source of investments
- The assessee submitted a reply on 12.01.2024, asserting his non-resident status and providing supporting documents, including passport copies and computation of income
- The AO passed the assessment order under Section 147 r.w.s. 144 on 28.03.2024, making additions of:
- Rs. 13,17,000 under Section 69A for unexplained cash deposits
- Rs. 15,00,000 under Section 69 for unexplained investment in immovable property
- The assessee contended that Rs. 8,96,000 of the cash deposits were sourced from gifts from family members, and the property investment was funded by the sale of another property for Rs. 11,50,000
Procedural History
- 15.12.2023: Notice under Section 142(1) issued by AO
- 12.01.2024: Assessee submits reply asserting non-resident status
- 28.03.2024: AO passes assessment order under Section 147 r.w.s. 144 without issuing draft order
- 08.08.2025: CIT(A) dismisses the assessee's appeal, upholding the AO's order and remanding the case for fresh assessment under the proviso to Section 251(1)
- 25.06.2026: ITAT hears the appeal
- 07.07.2026: ITAT pronounces order, quashing the assessment
The Parties' Positions
For the Appellant
- Argued that the assessee was a non-resident and thus an eligible assessee under Section 144C(15)(b)(ii) of the Act
- Contended that the AO was mandated to issue a draft assessment order under Section 144C(1) before passing the final order
- Submitted that the failure to follow this procedure rendered the assessment void ab initio, irrespective of the merits of the additions
- Highlighted that the AO's own order acknowledged the assessee's non-resident status, yet no draft order was issued
For the Respondent
- The Departmental Representative (DR) did not controvert the assessee's non-resident status
- Failed to justify the AO's omission to issue a draft assessment order under Section 144C
Relief Sought
The assessee sought:
- Quashing of the assessment order dated 28.03.2024 on grounds of procedural non-compliance
- Deletion of additions of Rs. 13,17,000 and Rs. 15,00,000 made under Sections 69A and 69 respectively
- A declaration that the assessment was void ab initio due to the AO's failure to follow Section 144C
The Legal Issue
The central question before the Tribunal was:
Whether the Assessing Officer's failure to issue a draft assessment order under Section 144C(1) of the Income Tax Act, 1961, for a non-resident assessee renders the entire assessment void ab initio, even if the assessee's residential status was admitted and the merits of additions were not adjudicated?
Arguments Presented
For the Appellant
- Relied on Section 144C(1) and Section 144C(15)(b)(ii), which define an eligible assessee to include non-residents
- Argued that the mandatory procedure under Section 144C requires the AO to first issue a draft assessment order, provide it to the assessee, and allow an opportunity to file objections before the Dispute Resolution Panel (DRP)
- Contended that the AO's failure to follow this procedure vitiated the entire assessment, making it void ab initio
- Emphasized that the AO's own order acknowledged the assessee's non-resident status, yet no draft order was issued
For the Respondent
- The DR did not contest the assessee's non-resident status
- No arguments were advanced to justify the AO's procedural lapse
The Court's Analysis
The Tribunal conducted a strict statutory interpretation of Section 144C, emphasizing its mandatory procedural safeguards for non-resident assessees. The key observations were:
-
Admitted Non-Resident Status: The AO's own assessment order acknowledged that the assessee was a non-resident, as evidenced by the assessee's submissions and passport records. This admission triggered the applicability of Section 144C.
-
Mandatory Nature of Section 144C: The Tribunal held that Section 144C(1) imposes a non-discretionary duty on the AO to issue a draft assessment order for non-resident assessees. The provision states:
"The Assessing Officer shall, notwithstanding anything to the contrary contained in this Act, in the first instance, forward a draft of the proposed order of assessment (hereafter in this section referred to as the draft order) to the eligible assessee if he proposes to make, on or after the 1st day of October, 2009, any variation which is prejudicial to the interest of such assessee."
The Tribunal noted that the use of the word "shall" in the statute indicates a mandatory requirement, not a directory one.
-
Procedural Safeguards: The Tribunal underscored that Section 144C is designed to provide additional layers of protection to non-resident assessees, including:
- The right to receive a draft assessment order
- The opportunity to file objections before the Dispute Resolution Panel (DRP)
- The right to a final order based on the DRP's directions
The Tribunal held that these safeguards are not mere formalities but essential components of natural justice in tax proceedings.
-
Void ab initio: The Tribunal ruled that the AO's failure to issue a draft order rendered the entire assessment void ab initio, regardless of the merits of the additions. The judgment stated:
"The provision of law contained in Section 144C requiring a draft order to be passed by the AO while framing assessment in the case of a non-resident is clear. The provisions of Section 144C therefore, clearly applied to the facts of the present case requiring the AO to pass a draft assessment order initially u/s 144C(1) of the Act. The AO having failed to do so, the order passed u/s 147 is legally unsustainable and is accordingly quashed."
-
No Adjudication on Merits: Since the Tribunal quashed the assessment on procedural grounds, it did not adjudicate the merits of the additions under Sections 69A and 69 or the assessee's explanations regarding the source of funds.
The Verdict
The Tribunal allowed the appeal and quashed the assessment order dated 28.03.2024 in its entirety. The key holdings were:
- The assessment order passed under Section 147 r.w.s. 144 was void ab initio due to the AO's failure to issue a draft assessment order under Section 144C(1)
- The additions of Rs. 13,17,000 and Rs. 15,00,000 were not adjudicated as the assessment was quashed on procedural grounds
- The CIT(A)'s order dated 08.08.2025 was set aside
- The remaining grounds of appeal were not considered as they became infructuous
What This Means For Similar Cases
Procedural Compliance Is Non-Negotiable
This judgment reinforces that statutory procedural requirements under the Income Tax Act are not mere technicalities but mandatory safeguards that must be strictly followed. Practitioners should note:
- Non-resident assessees are entitled to additional procedural protections under Section 144C, including the right to a draft assessment order and an opportunity to approach the DRP
- Failure to follow these procedures renders the assessment void ab initio, even if the assessee's residential status is admitted and the merits of additions are not adjudicated
- No discretion: The use of "shall" in Section 144C(1) leaves no room for discretion - the AO must issue a draft order for non-residents
Strategic Implications for Tax Litigation
- Grounds of Challenge: Assessees can challenge assessments on procedural grounds alone, even if the merits of additions are strong. This judgment provides a powerful tool to quash assessments without delving into factual disputes
- Burden of Proof: The onus is on the AO to comply with procedural requirements. Assessees need not prove prejudice - non-compliance itself is fatal
- Remand Risks: The Tribunal's decision to quash the assessment entirely (rather than remand for fresh assessment) highlights the high threshold for procedural lapses. Assessees should argue for outright quashing where procedural non-compliance is established
Key Takeaways for Practitioners
- Audit Trail: Always maintain documentary evidence of residential status (e.g., passport records, stay calculations) to establish non-resident status
- Procedural Scrutiny: Scrutinize assessment orders for compliance with Section 144C if the assessee is a non-resident. Non-issuance of draft order is a complete defense
- Appeal Strategy: In appeals, lead with procedural grounds where applicable, as they can trump substantive disputes and lead to outright quashing
- DRP Opportunity: If a draft order is issued, assessees should proactively file objections before the DRP to avoid final adverse orders
This judgment serves as a landmark precedent for non-resident assessees, emphasizing that procedural compliance is not optional and can be a decisive factor in tax litigation.